
Last updated: October 26, 2026
Commercial Equipment Financing for Trucks, Trailers, Machines and Software
Spread the cost of the vehicles, machines, furniture and software your business depends on over a set term.
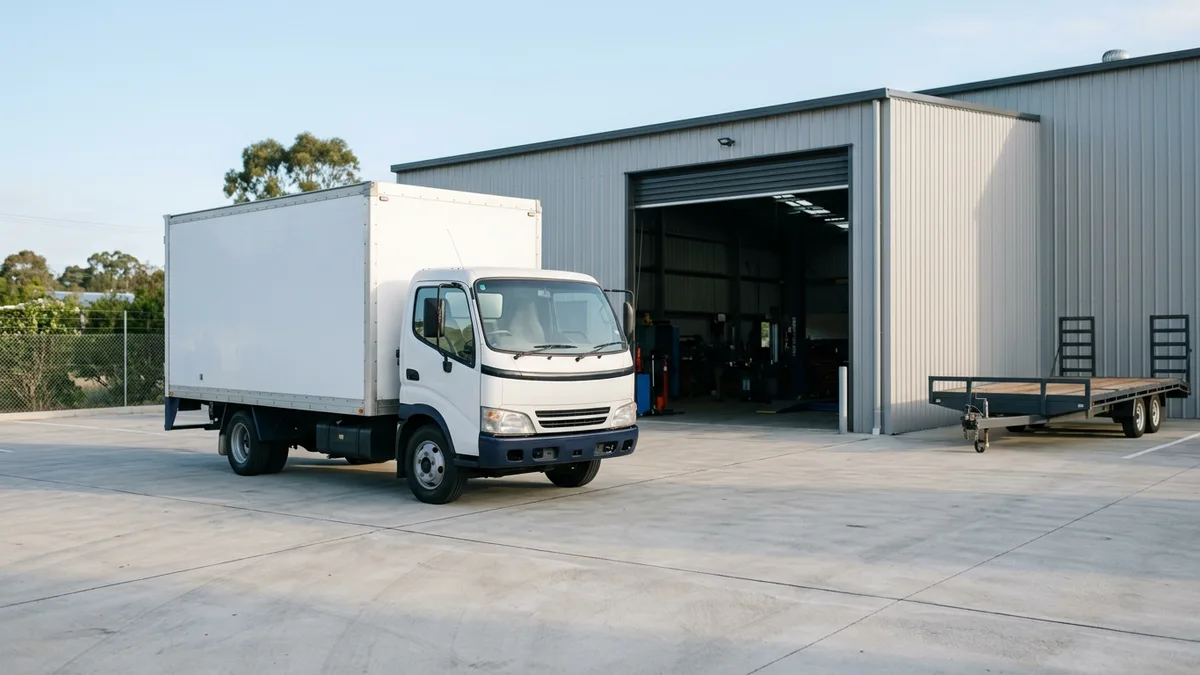
Commercial equipment financing lets a business pay for trucks, trailers, machines, furniture and software over a set term, with the equipment itself usually serving as the collateral, so cash stays free for payroll, inventory and growth.
You’ve found the machine. Now what? Every owner hits the same question, buy it outright, lease it or finance it, and there’s no single answer, because it depends on how long the equipment will earn its keep.
Paramount Financial’s equipment financing and leasing programs are the starting point, and this page is the map. It covers what counts as commercial equipment, how the money moves and how a loan differs from a lease. Short on time? Jump to the questions at the bottom.
What counts as commercial equipment
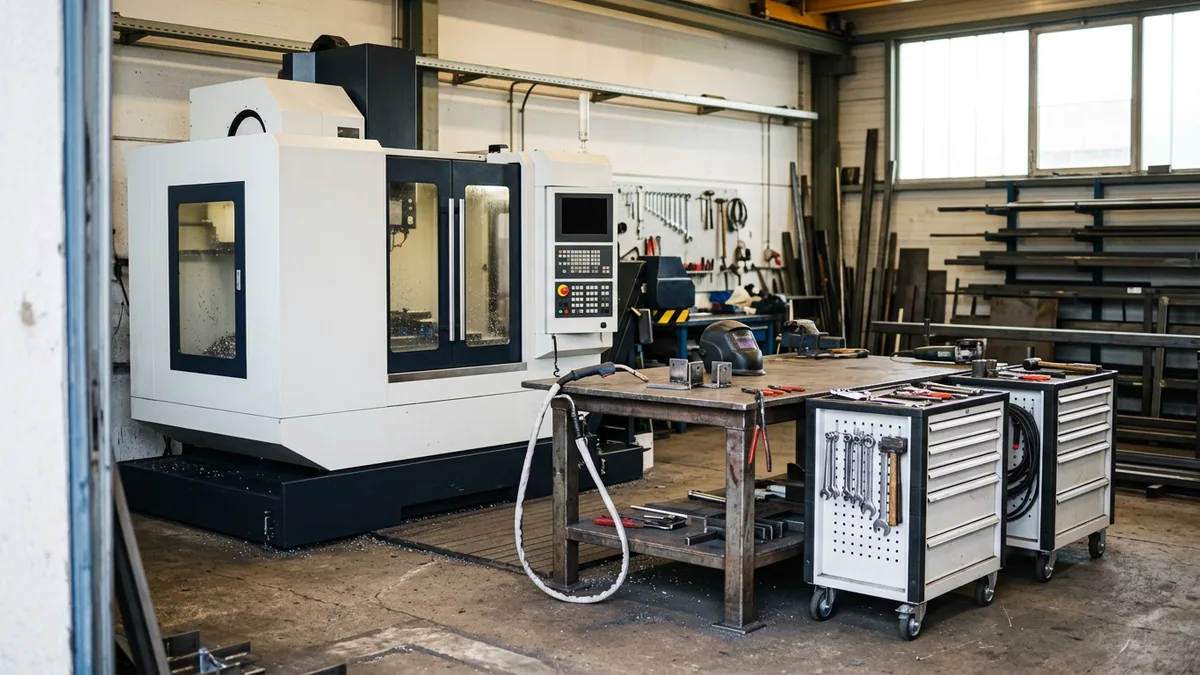
Picture two buckets. Titled equipment, such as box trucks, tow trucks and flatbed, dump or reefer trailers, carries a registration and a lienholder on the title. Untitled equipment, such as CNC machining centers, printing presses, welding cells and lab instruments, is tracked by serial number instead. A dental practice adding imaging, a regional fleet adding tractors and a cabinet shop adding a router all start by working out which of those two buckets the purchase belongs in, before anyone asks for a quote.
Then there’s the softer side of a build-out. Desks and seating, point-of-sale hardware, digital signage and business software often get bought alongside the machines. Trade matters too, so see equipment financing by industry if you work in construction, medical, restaurants or trucking.
How commercial equipment financing works
Commercial equipment financing is an arrangement where a lender pays for business equipment up front and the business repays it over a set term, with the equipment itself serving as collateral. The lender typically records its interest in the equipment, and the arrangement ends when the balance is paid or the lease runs out.
Here’s the flow. A lender pays the seller. You repay the lender. Because the equipment secures the deal, the lender usually files a UCC-1 financing statement, a public notice that names both sides and describes the collateral, as the Uniform Commercial Code’s section 9-502 sets out.
What a lender weighs beyond the quote
None of these is a pass-fail test on its own, because lenders weigh the equipment, the seller, the operating history and the owner’s profile together, and strength in one can offset weakness in another. Government-backed programs such as the SBA’s 504 loan can also fund long-term machinery and equipment with a useful remaining life of at least 10 years, so they’re worth comparing. That’s why the conversation matters.
Loan, finance agreement or lease: who owns what
The two structures differ mostly in who holds title and what happens at the end. Neither wins every time. A business keeping a truck for ten years and a business swapping out its computers every three are asking different questions, so here’s the short version.
| Equipment loan or finance agreement | Equipment lease | |
|---|---|---|
| Who holds title | Generally the business, with the lender’s lien recorded | The lessor, until a purchase option is exercised |
| When the term ends | The business owns the equipment once the balance is paid | Return it, renew the lease or buy it, as the lease provides |
| Often considered when | The equipment will stay in service for many years | The equipment changes quickly, or the business wants a choice at the end |
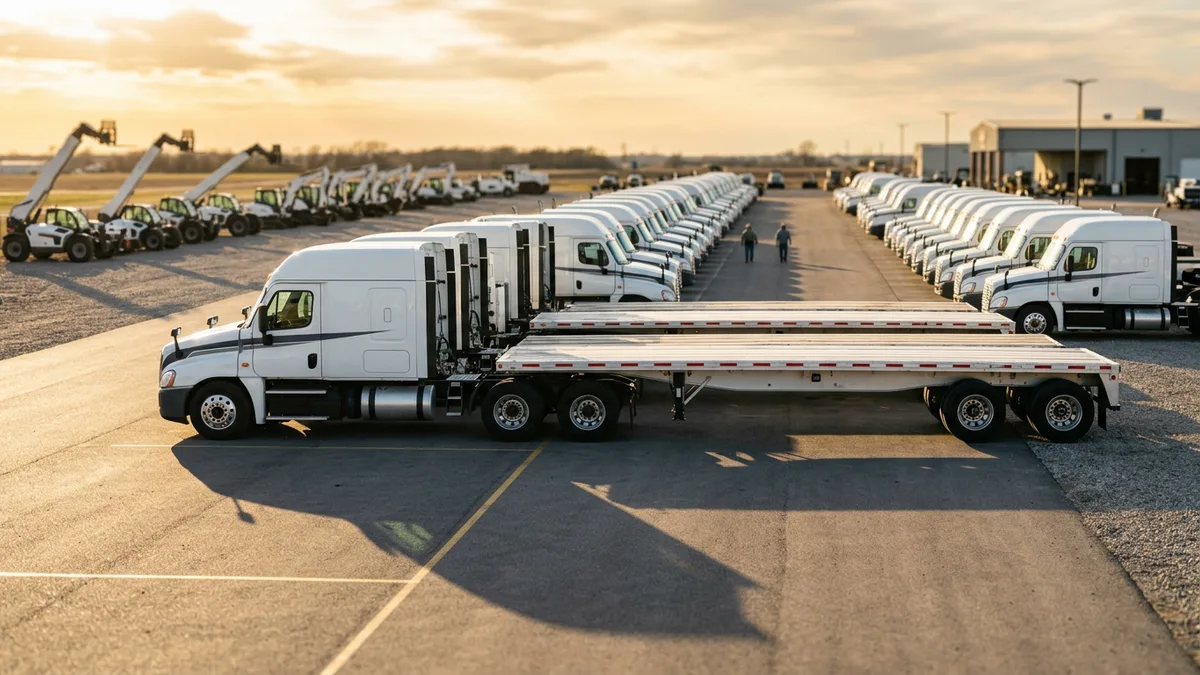
Leases come in several flavors. A fair market value lease prices the purchase at what the equipment is worth when the term ends, a $1 buyout lease is built so you keep the equipment, and a TRAC lease is common on titled vehicles like trucks and trailers. The tax treatment of a loan and a lease isn’t the same, so consult your tax advisor before you sign. Our equipment leasing page goes deeper, and the startup equipment financing page covers newer businesses.
Equipment financing in the numbers
82%
of equipment buyers used financing
Source: Equipment Leasing & Finance Foundation, Horizon Report, 2024
57.7%
of 2023 equipment investment financed
Source: Equipment Leasing & Finance Foundation, Horizon Report, 2024
26%
of 2023 acquisitions were leased
Source: Equipment Leasing & Finance Foundation, Horizon Report, 2024
Where to go from here
What owners ask before they finance equipment
So what can a business actually finance?
More than most owners expect: trucks, trailers, machines, desks, point-of-sale hardware and even software.
Take a box truck and a software license. The truck keeps its value for years. The license doesn’t. That gap changes how a lender structures each one, even when both sit in the same request.
How is an equipment loan different from a lease?
Ownership is the main difference: with a loan the equipment is yours from day one, and with a lease the lessor owns it until the term ends.
Say you want the machine for ten years, which points to a loan, or you expect to want a newer one in three, which points to a lease. Either way, compare the full agreements side by side, because the monthly figure hides a lot.
What happens to the equipment when a lease ends?
When a lease ends you usually have three options: return the equipment, renew the lease or buy the equipment.
Look for the purchase option. A fair market value lease sets the price at what the equipment is worth on the last day. A $1 buyout lease lets you keep it for a nominal sum. Read that clause before you sign.
Can you finance used equipment or a private-party purchase?
Three things decide it: how old the equipment is, who’s selling it and how much working life it has left.
Say the seller is another business owner, not a dealer, and the lender will want the title or serial numbers and a bill of sale, so have them ready. Ask early.
Do newer businesses get equipment financing?
A newer business has less history to show, so a lender leans harder on the equipment and the owner’s experience.
Picture a first-year shop buying a CNC machine. The lender can’t read years of statements, so it reads the machine’s resale value, the owner’s time in the trade and the cash flow behind the payment. Nothing here promises an outcome.
What is a UCC-1 filing on financed equipment?
A UCC-1 is the public record a lender files to claim its interest in the equipment behind a loan or lease.
Think of it as a sticker on the equipment, only public. It lists the borrower, the lender and a description of the collateral. That description can be tight, one machine, or broad enough to touch more of the business, so ask which a lender uses.
What should I have ready before I apply?
Bring the equipment quote or invoice, the seller’s contact information, and the business’s legal name and entity type.
Buying from a private party? Add the title or serial numbers. And jot down how long you plan to keep the equipment, because that note helps a lender weigh a loan against a lease.
Ready to put the equipment to work?
Tell us what the business needs and start your application, or leave your details below and a member of our team will follow up.