
Last updated: October 31, 2026
Bulldozer Financing: Loans and Leases for New and Used Dozers
How size, undercarriage and seller shape a dozer deal, and what to have ready before you apply.
Bulldozer financing spreads the cost of a crawler dozer, new or used, over a set term through a loan, an equipment finance agreement or a lease, with the machine itself usually standing behind the deal.
A dozer never shows up alone. There’s the blade, maybe a ripper, maybe a GPS grade system, plus a trailer big enough to move all of it. And if you’re like a lot of contractors, you aren’t shopping a showroom. You’re adding a used machine you found at a dealer’s yard, at auction or behind somebody’s barn.
This page sits under Paramount Financial’s heavy equipment financing overview and stays on the dozer: which size you’re buying, what a used one has to show, what a private sale adds and how a loan stacks up against a lease.
How bulldozer financing works
Bulldozer financing is an agreement where a lender or lessor pays for the dozer up front and the business pays over a set term. With a loan or an equipment finance agreement, the business owns the machine and the lender holds a security interest. With a lease, the lessor keeps ownership until the term ends.
Dozers don’t carry a title the way a truck does. So the lender records its interest on a UCC-1 financing statement, often describing the machine by serial number, and section 9-502 of the Uniform Commercial Code spells out what that notice has to contain. Our guide to what a UCC filing is covers the rest. It’s paperwork, not a judgment.
Bulldozer financing by size class
Start here. Size sets the budget, the trailer, the pool of used machines and how closely anyone will inspect the thing. Makers draw the lines a little differently, and Caterpillar’s own catalog files the D1 under small dozers, the D6 under medium and the D9 under large.
| Small | Medium | Large | |
|---|---|---|---|
| Examples | Cat D1 to D3 | Cat D4 to D8, Komatsu D51 and D61 | Cat D9 and up |
| Typical work | Finish grading, house lots, driveways | Site work, road building, land clearing, pipeline | Mass earthmoving, mines and quarries |
| Getting it to the job | A heavy-duty trailer and the right truck | Usually a lowboy | Heavy haul, often with permits and parts removed |
| What comes up on a used one | Hours, serial number, the seller’s invoice | All of that, plus undercarriage wear and blade condition | Often a formal inspection or an appraisal |
Crawler or wheel dozer?
Almost everything on this page means a crawler, on steel tracks. Wheel dozers, the rubber-tired kind you’ll see around mines and ports, are a rarer purchase with fewer comparable sales to price against, so expect more questions about value.
Used bulldozer financing starts at the undercarriage
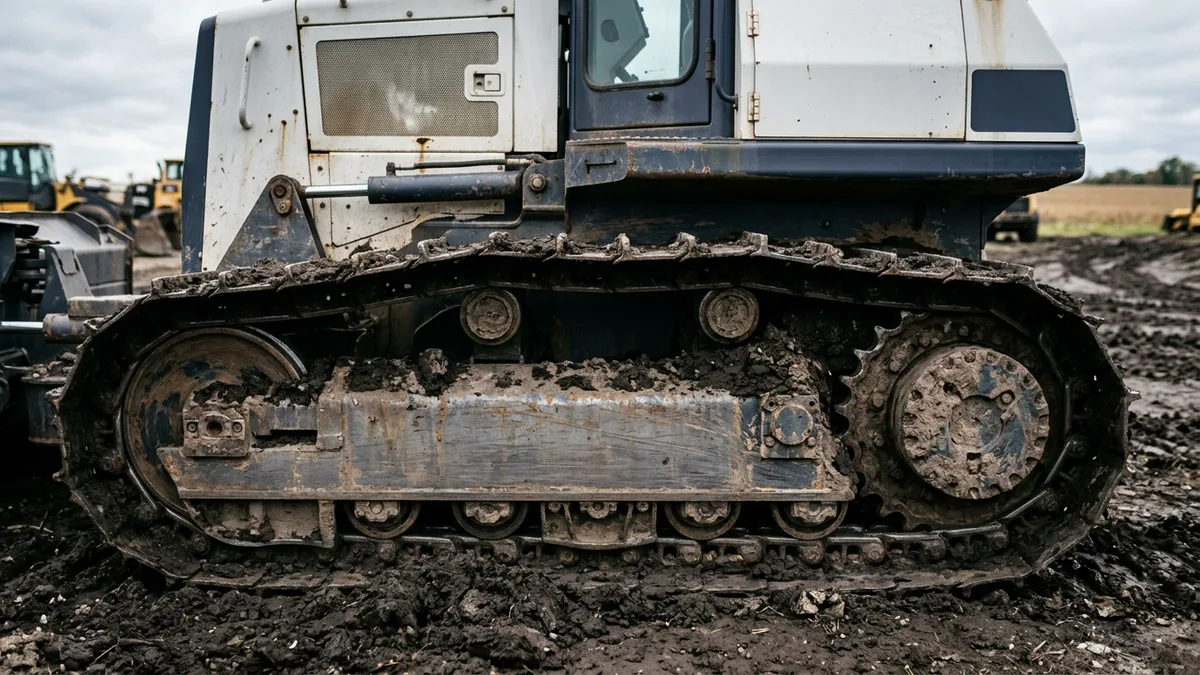
Everyone asks about engine hours. The tracks are where the money goes. Rollers, idlers, links and sprockets wear out on a schedule of their own, and replacing them is a big bill, so a well-kept machine with high hours can beat a neglected one with half as many.
Next, start it up. ConEquip, a parts and equipment seller, says in its used bulldozer buying tips to let one idle at least 15 minutes and then go hunting for leaks. A seller who won’t fire it up has answered your question.
We’d also spend money on an undercarriage inspection, the kind with calipers and written numbers. Lenders like facts. So will you, at resale. OSHA’s earthmoving rule names the seat belt, rollover protection and the horn, so test them while you’re standing there, and see used equipment financing for dealer versus private seller in general.
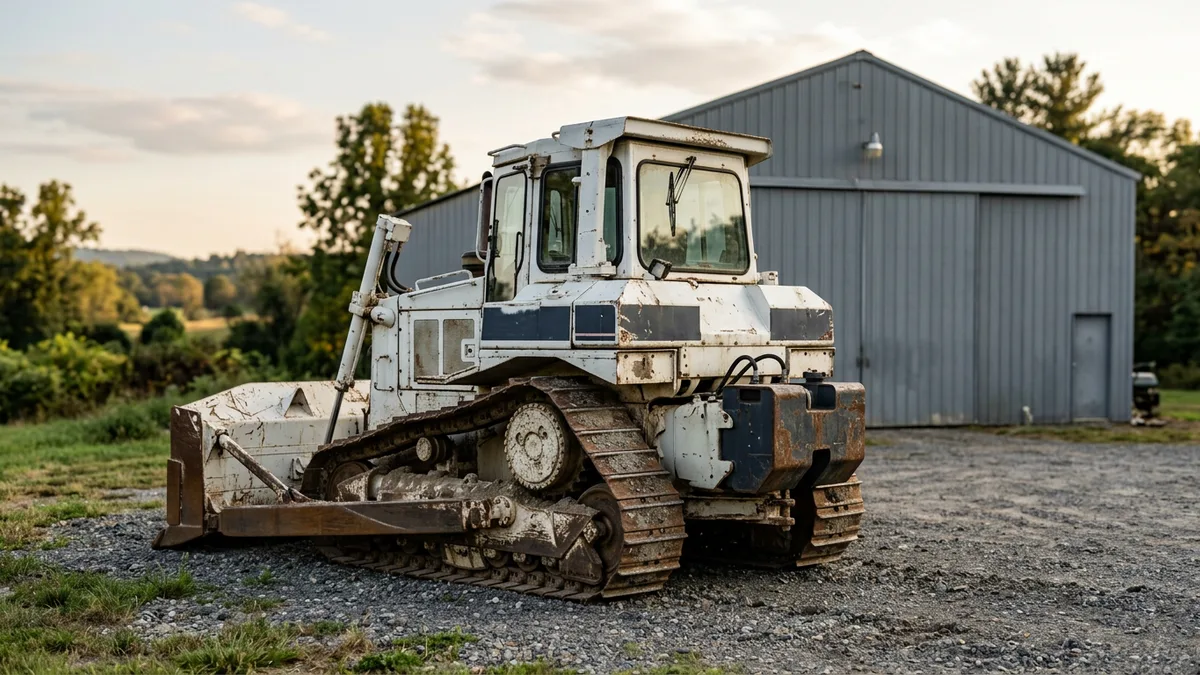
Private-party dozer financing: the paperwork falls to you
Picture a retiring contractor down the road, selling the dozer that’s sat behind the shop since spring. No warranty comes with it. You’re doing the clerk’s job now.
Old liens are what bite people. Section 9-315 of the Uniform Commercial Code generally keeps a security interest attached to collateral after a sale, unless the secured party agreed otherwise, and that means whatever the seller still owes on the machine could come home with you on the trailer. A UCC search in the seller’s state takes care of the guessing. If a balance shows up, ask for a payoff letter before anybody gets paid.
Auctions? Different animal. Short payment windows, and the sale’s usually final, so call your lender before you raise a hand. Not every lender treats a private sale the same way, either.
Dozer financing or a lease: which fits the work
Ten years on the machine, an undercarriage rebuild along the way and a sale of your own at the end? That points toward owning it, with a loan or a $1 buyout lease. A two-year contract is a different story. A fair market value lease might fit, since you can hand the dozer back when the work ends, but read the return conditions on tracks and hours slowly, and our page on construction equipment leasing compares the structures.
Now the invoice. It can hold more than the tractor.
Ask whether a lender will fold those into one agreement. Taxes come next. For tax years beginning in 2026, IRS Publication 946 caps the Section 179 deduction at $2,560,000, and it’s elected on Form 4562. A loan and a lease can land differently, so consult your tax advisor, and read our Section 179 deduction guide first.
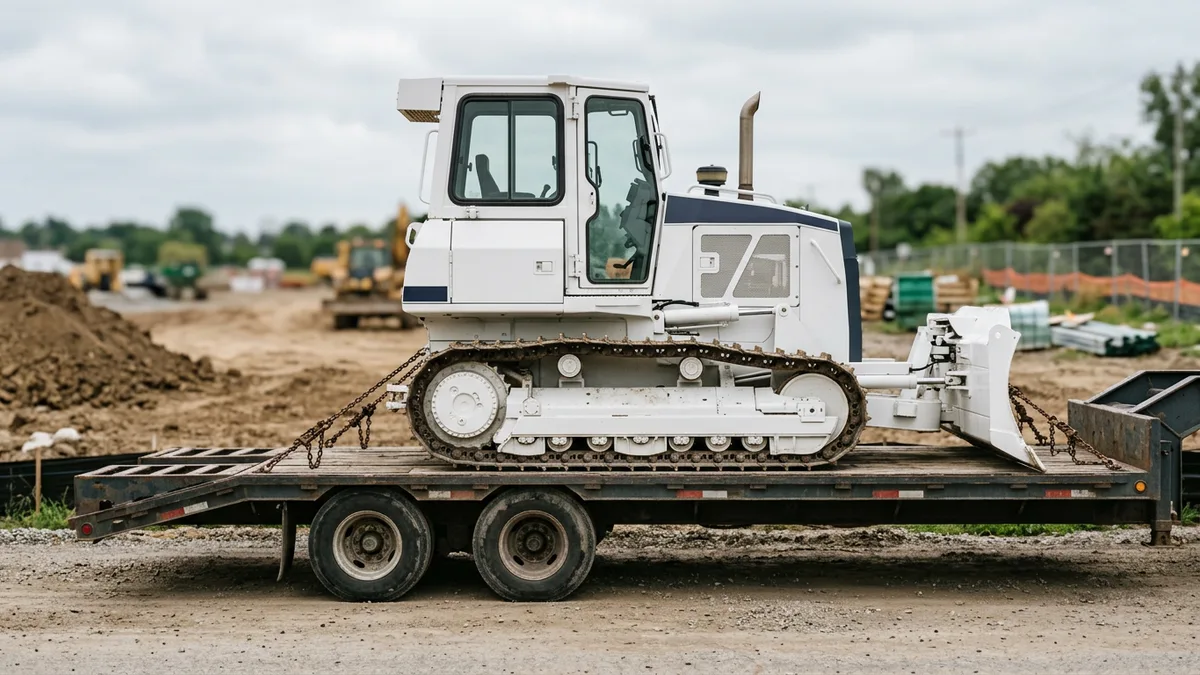
What you’ll actually be hauling
Weight decides the trailer, the truck and sometimes the permit, and those costs come out of the same budget as the payment. Options change it too. Caterpillar adds 1,222 pounds for a ripper on that D1.
Three crews, three different dozers
More on heavy iron and how financing works
What contractors ask before financing a dozer
So how does bulldozer financing actually work?
A lender pays the seller, and the business repays over an agreed term with the dozer as collateral. That’s the loan version. On a lease, the lessor owns the machine until the end, and then you return it, renew or buy it, depending on what the lease says.
Can you finance a used bulldozer?
Short answer: lenders do finance used dozers, but they look harder at them than at new ones. Undercarriage life, hours, service records and the seller all come up. No single age or hour cutoff applies everywhere. Ask first.
What changes if the dozer comes from a private seller?
More of the paperwork lands on you: a bill of sale, the serial number, the hour reading and a lien search. Check for an old loan first. If there is one, it has to be paid off or released, and that’s far easier to sort out before the sale than after it.
Should I lease or buy a dozer?
The better question is how long this machine will stay on your jobs. For years and years, owning tends to make sense, while a lease can suit a single long contract or a shop that likes to change machines often. Tax treatment differs, so consult your tax advisor.
Can GPS grade control and a ripper go on the same agreement?
It usually comes down to whether they’re on the same invoice as the machine. Factory-fitted options generally are. An aftermarket kit bought three months later may become a separate small deal. Check before you order.
What slows a bulldozer financing request down?
Paperwork, nine times out of ten. Think of a serial number that doesn’t match the bill of sale, or a lien nobody knew about until the search came back. An older machine with no inspection report and no service history will draw more questions as well, and a seller who’s slow to call back with the answers doesn’t help anybody.
Does a bulldozer qualify for Section 179?
Section 179 can cover equipment a business buys and uses for work, though whether yours fits depends on how it’s acquired and used. IRS Publication 946 sets the 2026 cap at $2,560,000. Don’t count on a number until you’ve talked to your tax advisor.
Found the dozer you want?
Send us the machine, the seller and a few details about the work, then start your application, or leave your details below and a member of our team will follow up.