
Last updated: October 27, 2026
Skid Steer Financing for New and Used Machines
Pay for the loader, its attachments and the trailer over a set term.
Skid steer financing lets a business pay for a skid steer loader, and often the attachments that go with it, over a set term, with the machine itself usually serving as collateral, whether it’s bought new or used.
Skid steers rarely sit still. One day it’s pallet forks in a yard, the next it’s an auger on a fence line, so the payment has to suit a business that’s busy, sometimes stretched and not always flush when the invoices come due.
This page sits under Paramount Financial’s heavy equipment financing overview. It walks through the choices that shape a skid steer deal, from wheels versus tracks to new versus used, plus attachments and the loan-or-lease question. Trades differ too, so the equipment financing by industry page shows how buying patterns change from one trade to the next.
How skid steer financing works
Skid steer financing is an arrangement where a lender pays for the machine up front and the business repays it over a set term, usually with the skid steer itself as collateral. Some deals are loans, some are leases, and plenty bundle the attachments with the machine.
Because the machine secures the deal, the lender usually files a UCC-1 financing statement that describes it, often by serial number, and section 9-502 of the Uniform Commercial Code says what that notice has to contain. Our guide to what a UCC filing is covers the rest. Short version? It names the collateral, and it isn’t a verdict on your business.
Wheeled or track: what the ground decides
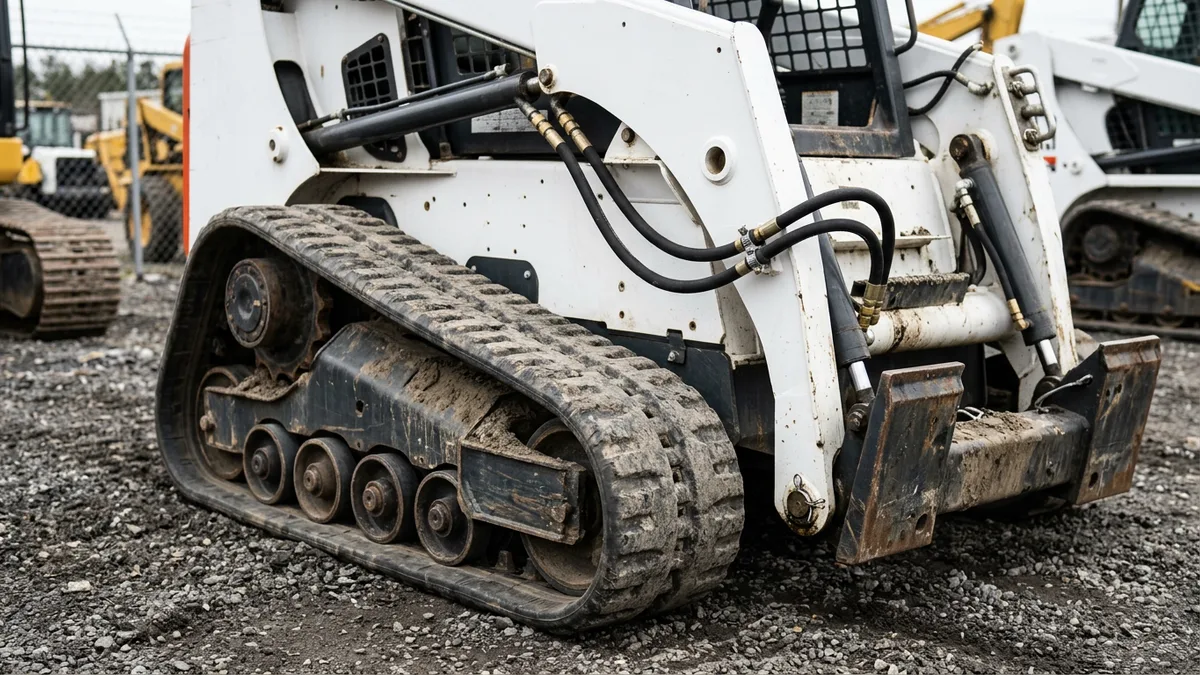
Pick the carrier first. It changes what the machine costs to keep running over the years, and it changes what a lender sees when the machine is used, with tire wear on one side and undercarriage wear on the other. Wheels suit firm ground, and tracks float over soft ground. Neither is better in the abstract. Our skid steer cost guide sets Bobcat’s published list prices for both carriers side by side.
| Wheeled skid steer | Compact track loader | |
|---|---|---|
| Ground it suits | Pavement, gravel, packed dirt and other firm surfaces | Mud, sand, snow and soft or finished turf |
| What wears out | Tires, which scuff and cut on rough or sharp ground | Rubber tracks, rollers and sprockets, the undercarriage |
| Check on a used one | Tread depth, sidewall damage and flat spots | Track wear, roller and sprocket condition, and track tension |
| Typical jobs | Yard work, pallet handling, grading gravel, landscaping on firm soil | Site prep, grading, trenching, work on wet or soft ground |
Loan or lease for a skid steer
With a loan or an equipment finance agreement, the business owns the machine and the lender holds a security interest. With a lease, the lessor owns it until the term ends. A $1 buyout lease is built so the business keeps the skid steer, while a fair market value lease sets the buyout at what the machine is worth on the last day.
Our equipment leasing page goes deeper, and the guide to operating and finance leases compares the two lease types. The equipment lease agreement guide lists the key terms to read first. Tax treatment differs between a loan and a lease, so consult your tax advisor before you sign.
Used skid steer financing: what lenders look at
Used machines vary the most, so a lender leans on the details. Age and hours come first. Condition comes right behind.
Skid steers usually aren’t titled like trucks, so the serial number plate and the bill of sale carry the weight. Buying from a private party? Get both in writing before any money moves. Machines from familiar makers such as Bobcat, Case, Kubota and John Deere are easier to price against comparable sales, though that’s a factor, not a guarantee.
Safety gear matters too. Check that the seat belt, the control interlocks and the cab structure are intact, and skim NIOSH’s alert on preventing injuries and deaths from skid-steer loaders before you buy.
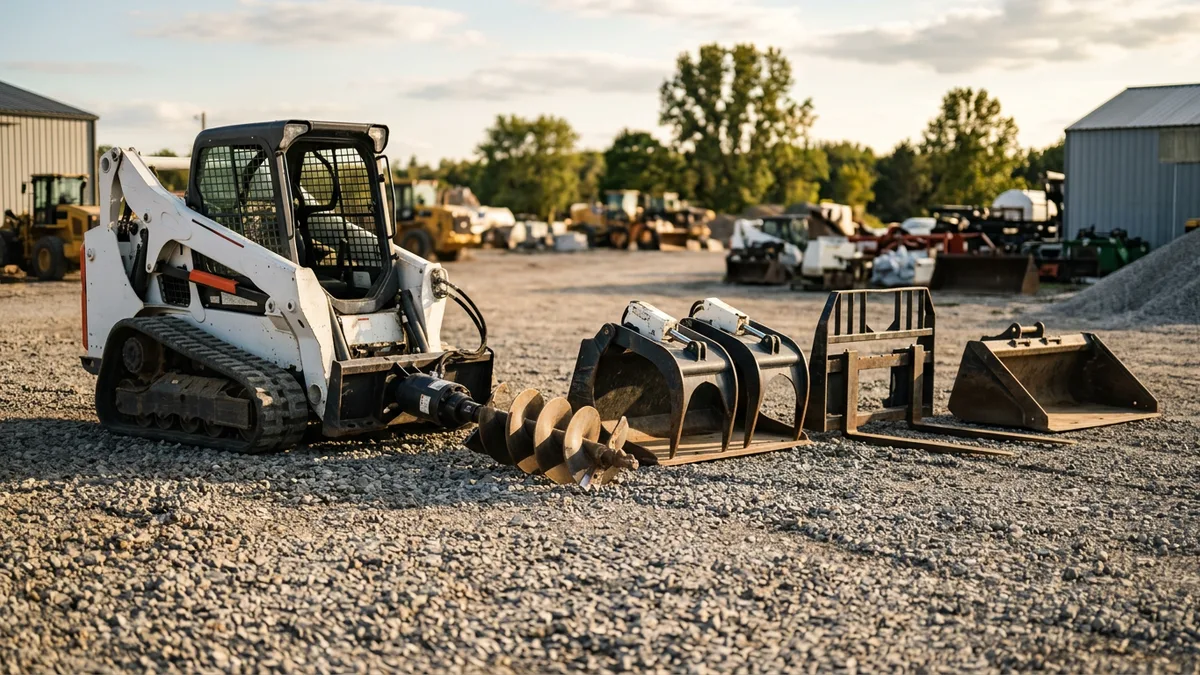
Skid steer attachment financing: the bucket is only the start
A skid steer earns its keep through what’s on the front. Each attachment turns the same carrier into a different line of work.
Two details trip people up. Some attachments need a high-flow auxiliary hydraulic system, and every one has to fit the machine’s quick-attach coupler. Check both before you order.
Then ask whether the attachments can ride on the same agreement as the machine. Lenders differ here. One may bundle everything into a single payment, another may treat each attachment as its own small deal. For trucks, trailers and gear beyond the loader, see commercial equipment financing.
Why equipment buyers choose to finance
62%
named cash flow as a top reason to finance
Source: Equipment Leasing & Finance Foundation, Horizon Report, 2024
55%
named protection from obsolescence
Source: Equipment Leasing & Finance Foundation, Horizon Report, 2024
26%
of 2023 acquisitions were leased
Source: Equipment Leasing & Finance Foundation, Horizon Report, 2024
Keep reading before you apply
What skid steer buyers ask before they finance
So how does financing a skid steer actually work?
A lender pays the seller, and you repay the lender over a set term while the skid steer serves as collateral.
That’s the loan version. In a lease, the lessor owns the machine until the term ends, and then you return it, renew or buy it, so which one fits depends on how many seasons you plan to run the machine and what you want at the end.
Can you finance a used skid steer?
Short answer: lenders do finance used skid steers, but they study them harder than new ones.
Hours, age, maintenance records and the seller all count. A private sale needs a clean bill of sale and the serial number. Ask early.
Does attachment financing come with the machine?
The better question is whether the attachments sit on the same invoice as the machine.
When they do, many lenders can fold everything into one agreement. When they don’t, an attachment may become a separate small deal. Terms differ. Ask before you order.
Should I lease or finance a skid steer?
Three things decide it: how long you’ll keep the machine, how many hours a year it will run and what you want at the end.
Keep it ten years and a loan points one way. Swap it every few seasons and a lease points the other. Tax treatment differs, so consult your tax advisor before you sign.
Can I finance a skid steer I’m renting right now?
A rental-purchase option is a clause that lets you buy the machine you’re renting, and that clause is where the answer starts.
Read the rental agreement for the buyout price and any rental credit toward it. Then ask a lender whether it will pay that price. Don’t assume it will.
What slows a skid steer financing request down?
Missing paperwork does most of the damage.
A serial number that doesn’t match the bill of sale can stall a file. So can an unsigned invoice, or one that leaves the attachments off. A slow seller doesn’t help either.
What should I have ready before I apply?
Bring the invoice or quote, the seller’s contact details and the business’s legal name and entity type.
For a used machine, add the serial number. For a private sale, add a draft bill of sale. A short note on how many hours a year the machine will run helps a lender weigh a loan against a lease, and it helps you too, because it forces the question of whether you’ll still want this machine in five years.
Got a skid steer in mind?
Tell us about the machine and the attachments, then start your application, or leave your details below and a member of our team will follow up.