
Last updated: November 3, 2026
Paving Equipment Financing: New and Used Pavers, Rollers and Milling Machines
What a paving crew buys, what to check on used machines, and how a loan or lease fits.
Paving equipment financing lets a contractor buy or lease pavers, rollers and milling machines, then pay over a set term, usually with the equipment itself securing the deal.
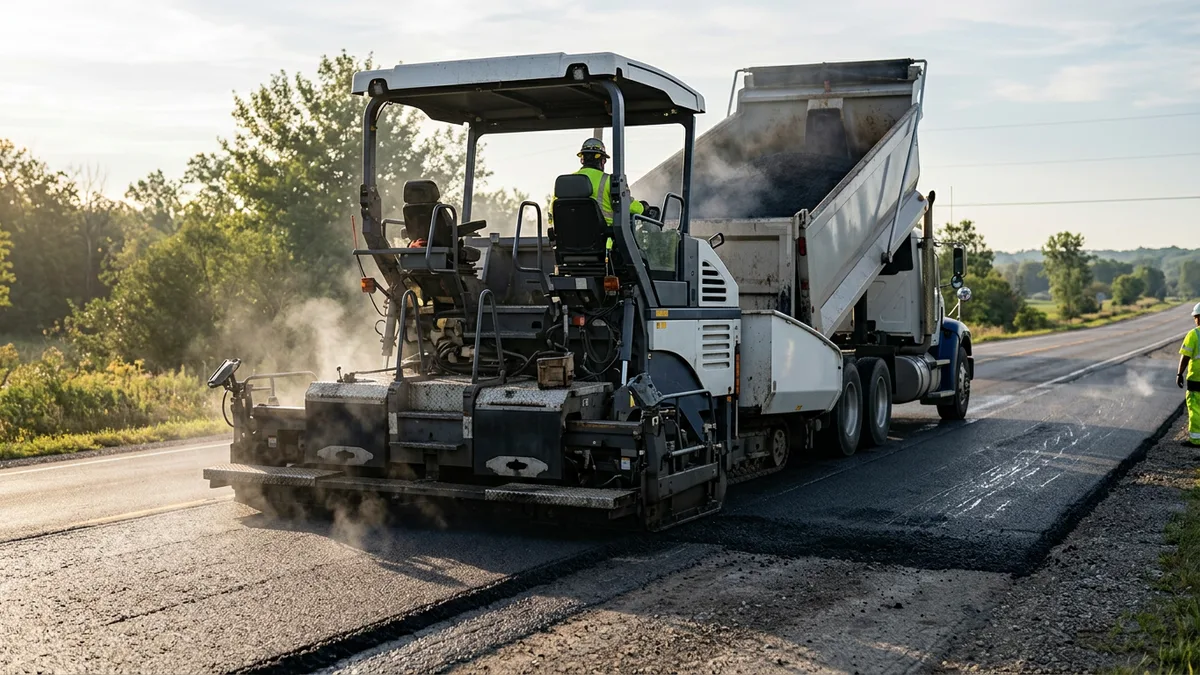
A paver doesn’t work alone. Rollers follow it, a milling machine often goes ahead, and trucks keep the hopper full, so a paving purchase is rarely one machine. Many buy used. From a dealer’s lot, or a retiring crew down the road.
This page sits inside our heavy equipment financing guide and stays on the asphalt side: which machines make up a crew, what to check on a used one, and how a loan stacks up against a lease.
How paving equipment financing works
Paving equipment financing means a lender pays for the machine and you pay it back over an agreed term. With a loan or an equipment finance agreement, you own the paver from day one and the lender holds a security interest. With a lease, the lessor owns it until the term runs out.
Titles matter here. Trucks and trailers carry them. Pavers, rollers and mills usually don’t. So a lender typically records its interest on a UCC-1 financing statement and describes the machine by serial number, and our guide to what a UCC filing is covers the rest.
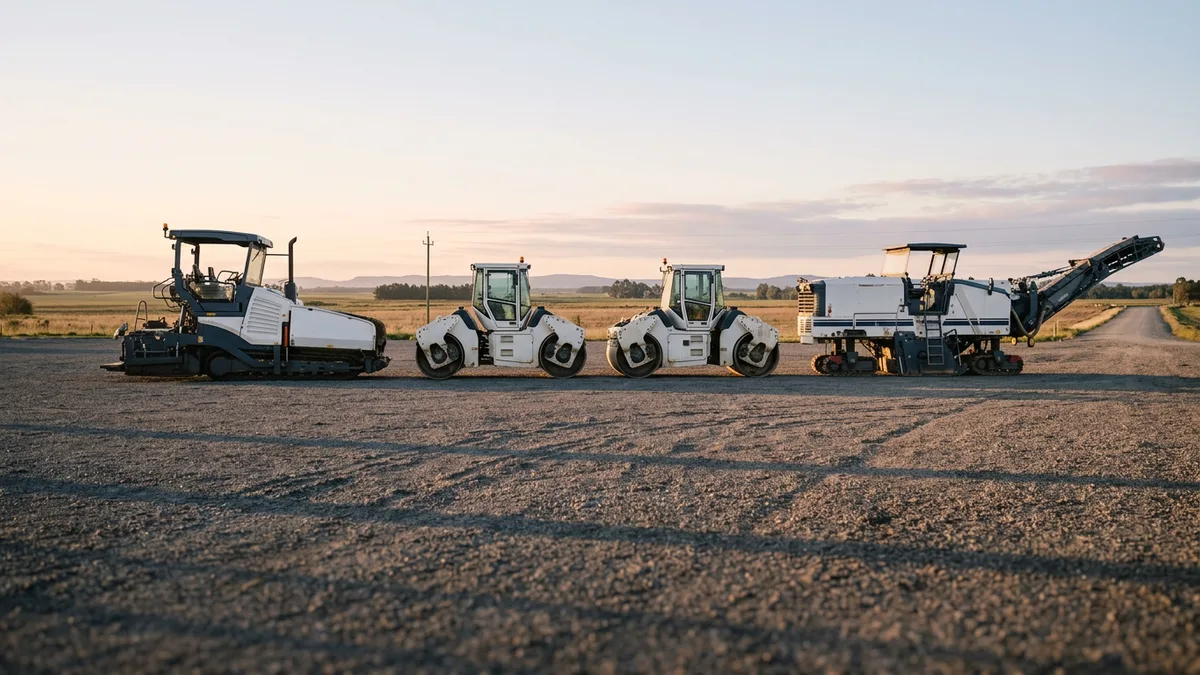
The paving crew, machine by machine
Here’s the order a crew runs down the road. Mill first. Then the distributor sprays tack coat, trucks or a transfer vehicle feed the paver, and the rollers go over the fresh mat last, each of them a separate line on an invoice.
| Machine | What it does | Worth checking on a used one |
|---|---|---|
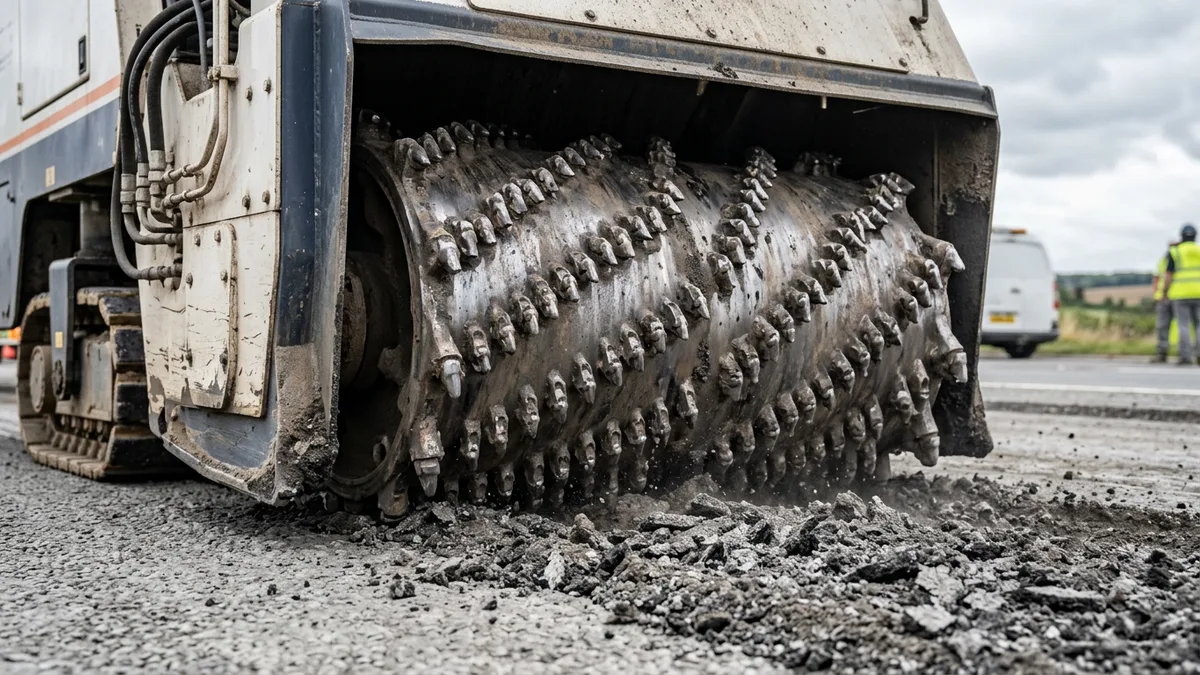
| Milling machine | Grinds off the worn surface so a road can be resurfaced | Cutter drum, teeth and holders, water sprays |
| Asphalt distributor | Sprays tack coat so the new mat bonds to the old surface | Spray bar, pump and tank, plus the truck itself |
| Material transfer vehicle | Takes mix from the trucks and feeds the paver without a stop | Conveyors and hopper |
| Paver | Spreads hot mix from its hopper into an even mat | Screed plates, augers and slat conveyor |
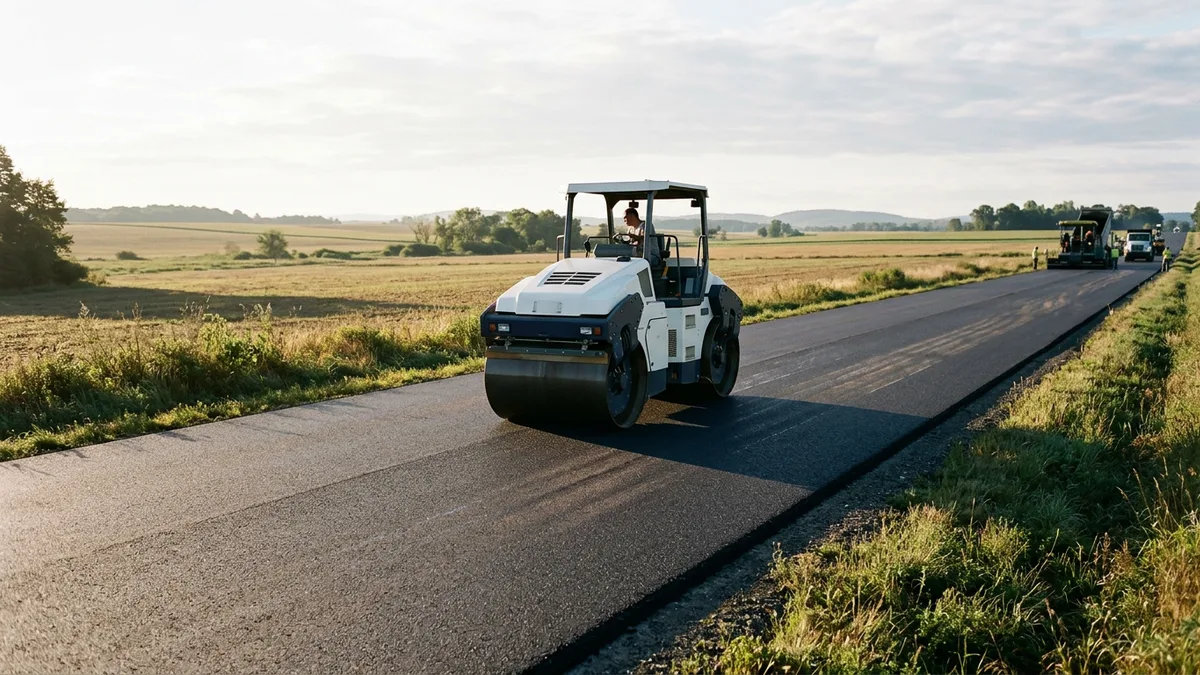
| Roller | Compacts the mat in passes behind the paver | Drum surfaces, vibration and the water spray system |
Not everyone needs all five. A parking-lot contractor may never own a mill, and a milling specialist may never touch a paver, so price the set you’ll actually run on the job, not just the paver.
Used paving equipment financing starts at the wear parts
Hours on the meter only tell part of it. Wear hides elsewhere: in a paver’s screed plates, augers and slat conveyor, in a mill’s cutter drum and teeth, in a roller’s drum surface and the vibration system that drives it. Look there first.
A used mill raises one more question. OSHA’s silica standard, 29 CFR 1926.1153, spells out dust controls for drivable milling machines: water sprays on every size, plus exhaust on the drum enclosure for half-lane machines and larger. Ask to see them working.
Then the seller. A dealer hands the lender an invoice, a serial number and often a service history. A private seller may hand over a blank bill of sale. See used equipment financing for how the two compare.
Financing the whole crew, not just the paver
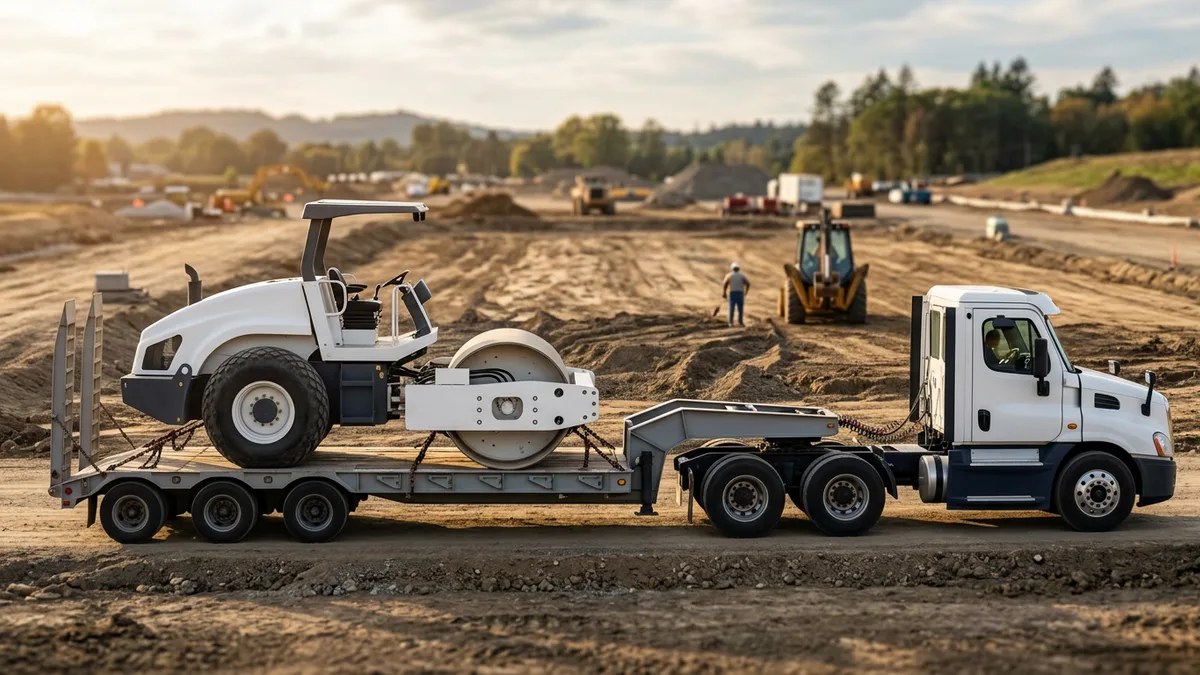
Picture a two-machine start: a paver and one roller. It works until a job calls for a second roller, a mill or a trailer to move any of it. Another purchase. Here’s what tends to land on a paving invoice.
Ask whether a lender will wrap them into one agreement or write each separately, because one schedule is simpler to track while separate agreements leave you more room to sell or swap a single machine later. Both have a case.
And watch the calendar. In colder states, hot-mix paving usually slows or stops for the winter, and a standard payment schedule doesn’t stop with it unless the agreement says so. Ask any lender whether a seasonal schedule is possible before you sign.
Asphalt equipment financing: a loan or a lease?
Start with how long the machine will stay in your crew. Three questions help.
A paver or roller you’ll run for a decade points toward owning it, through a loan or a $1 buyout lease. If you’d rather swap machines every few seasons, or you’re buying for a single contract, a fair market value lease can fit, since you return the machine, renew or buy it at the end. Our page on construction equipment leasing compares the structures.
Taxes can tip the choice. For tax years beginning in 2026, IRS Revenue Procedure 2025-32 sets the Section 179 limit at $2,560,000, elected on Form 4562. A loan and a lease can be treated differently, so consult your tax advisor before you count on a number, and read our Section 179 deduction guide first.
The machines and the road work behind them
30,430 lb
Cat AP555F track paver, paver only, before the screed
94%
of the 2.8 million miles of paved roads in the United States are surfaced with asphalt
432 million tons
of asphalt mixture produced in the United States in 2021
Cat lists the screed separately, at 7,239 pounds for the SE50 V, so one paver can show up as two lines on an invoice. Ask how a lender writes that up.
Four kinds of crews, four different shopping lists
More on construction equipment and how financing works
What paving contractors ask before they finance equipment
So what counts as paving equipment on a financing request?
Pavers, rollers, milling machines, material transfer vehicles and asphalt distributors all show up on paving requests, along with the trucks and trailers that serve them.
Smaller gear shows up too, like crack sealers and hot boxes. What a lender will fund depends on the lender, the machine and its age. Ask first.
So how does paving equipment financing actually work?
Short answer: the lender pays for the machine, and you pay the lender back over an agreed term, usually with the machine itself as collateral.
That’s a loan or an equipment finance agreement. A lease flips it. The lessor owns the paver or roller until the term ends, and then you return it, renew or buy it, depending on what the lease says.
Can you finance a used paver, roller or milling machine?
Lenders do finance used pavers, rollers and mills, and the machine’s age, hours and wear decide how closely they look.
Expect questions about the screed, the drums or cutter teeth, the service records and who’s selling. Dealer and private sales aren’t treated alike. No single age or hour cutoff applies everywhere.
Should I lease or buy a paver?
The better question is how long the machine will stay in your crew, because that points toward owning it or leasing it.
Run it for a decade? A loan or a $1 buyout lease usually fits. Shorter stretch, or one contract? A fair market value lease can fit, though tax treatment differs, so consult your tax advisor.
What do lenders ask about on a used milling machine or paver?
Three things come up first: the machine’s hours against its age, the condition of its wear parts, and a serial number that matches the paperwork.
Service records help. So does a short inspection report from a dealer or a mechanic, especially on an older machine or a private sale. On a mill, expect a question about dust controls too.
What happens to payments when paving slows down for the season?
A standard payment schedule keeps running through the slow season unless the agreement says otherwise, so ask about it before you sign.
Some lenders offer seasonal schedules. Some don’t. Ask whether one is possible, and what it does to the total cost. Know your own slow months before you ask, so the request is specific.
Does paving equipment qualify for Section 179?
Section 179 can cover qualifying equipment a business buys and uses in its work, though whether yours fits depends on how it’s acquired and used.
For tax years beginning in 2026, the limit is $2,560,000 under IRS Revenue Procedure 2025-32. A loan and a lease can be treated differently, and some leases aren’t treated as purchases at all. Consult your tax advisor before you count on anything.
Lined up the machines for your crew?
Tell us what you’re buying, who’s selling it and a bit about the work, then start your application, or leave your details below and a member of the Paramount Financial team will follow up.