
Last updated: October 27, 2026
Commercial Truck Financing: Vocational, Box and Semi Trucks for Contractors and Carriers
See how lenders review vocational, box and semi trucks, and what to have ready before you apply.
Commercial truck financing spreads the cost of a work truck over a loan or lease, and the lender weighs the truck’s weight class, age and job alongside the owner’s experience.
Contractors adding a dump truck, delivery businesses adding a box truck and owner-operators adding a tractor all end up asking the same thing. How will a lender look at the truck? That’s what this page covers.
It sits inside our wider guide to equipment financing by industry, where trucking is one trade among many. Here we stay with the truck itself, from its weight class to its title.
How commercial truck financing sorts vocational, box and semi trucks
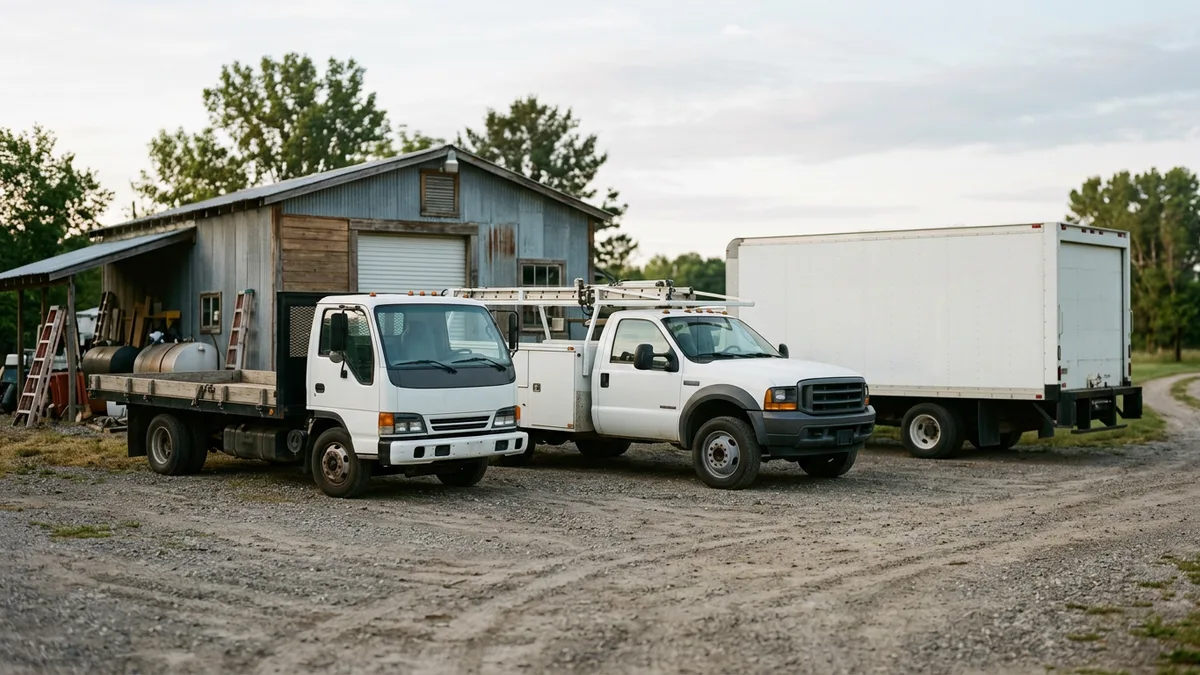
Commercial truck financing is a loan, equipment finance agreement or lease used to acquire a work truck or trailer, with the truck standing as the lender’s collateral or the lessor’s asset. Weight class, age, condition and the work it does shape how the review goes.
Weight is the quickest tell. The Department of Energy’s vehicle weight class table sorts trucks by gross vehicle weight rating (GVWR), the most a truck is built to carry fully loaded, so Class 3 starts at 10,001 pounds, Class 7 starts at 26,001 and Class 8 begins above 33,000.
Same structures across all three. A loan or equipment finance agreement makes the business the owner from day one, while a lease keeps ownership with the lessor during the term.
Why a titled truck carries its lien on the title
A truck is titled property, and that changes the paperwork. For most equipment a lender files a UCC-1 financing statement. For goods covered by a certificate-of-title law, UCC section 9-311 says the lender’s interest is perfected through that statute instead of a financing statement, which usually means the lienholder is named on the certificate of title.
So the title is the document that has to be clean. A seller whose name isn’t on it, an old lien nobody has paid off or a VIN that doesn’t match the bill of sale all stall a deal. Details differ by state. Each state runs its own title office, so check yours.
What to line up before you apply for truck financing
Every lender sets its own list, so treat this as a starting point. Get it ready early.
| Item | What the lender wants to see | What to bring |
|---|---|---|
| The truck | What it is, how old it is and what shape it’s in | A seller quote or bill of sale with the year, make, model, VIN and mileage |
| The seller | Whether it comes from a dealer, an auction or a private owner | The seller’s name and address and, for a private sale, a copy of the current title |
| The owner | Who runs the business and what they’ve driven or built | A driver’s license, a CDL if the truck calls for one and a short work history |
| The registration | Whether the truck hauls across state lines under its own registration | Your USDOT number and operating authority details, where they apply |
| Insurance | That the truck is covered | Proof of insurance on the truck, plus what the lender wants listed on it |
| The business | That the company exists and keeps its books in order | Formation papers, an EIN letter and recent business bank statements |
| An old loan | What’s still owed when a truck is being refinanced | A payoff letter and the current lien details from the title |
Start with the seller’s quote. Every other document hangs on it, because the VIN, the year and the mileage on the quote have to match the title, and the rest can follow in whatever order it arrives. Match every name and address.
Lease or buy? Our page on equipment leasing explains how the structures differ.
Three weight lines that shape a truck’s rules
10,001
Pounds of GVWR where an interstate truck counts as a commercial motor vehicle
Source: Federal Motor Carrier Safety Regulations, 49 CFR 390.5 (checked October 2026)
26,001
Pounds of GVWR where a straight truck falls in a CDL group
Source: Commercial driver’s license standards, 49 CFR 383.5 (checked October 2026)
33,001
Pounds of GVWR where Class 8, the heaviest federal class, begins
Four things a truck review turns on
Related equipment financing pages
Truck financing questions owners ask first
So how does commercial truck financing actually work?
A lender or lessor pays for the truck, and the business repays over an agreed term, with the truck itself backing the deal.
With a loan or equipment finance agreement, the business owns the truck and the lender holds a lien on its title. With a lease, the lessor owns the truck during the term. What it costs each month depends on the lender, the truck and the file, so get the structure in writing before you compare offers, and look at the total cost over the whole term, not only the monthly figure.
Can I finance a used commercial truck?
Short answer: often, and the truck’s age, mileage and condition are what a lender looks at first.
Every lender draws its own lines on age and miles, so one lender’s cutoff isn’t another’s. A clean title helps. So does a seller quote with the VIN and mileage. None of this is a promise about any one truck.
How does a new owner-operator get a truck financed?
Three things carry the most weight: the truck itself, the owner’s time behind the wheel and a paper trail that matches.
A new owner-operator has no carrier history to show, so a lender leans on what’s in front of it. Driving experience counts. So does a CDL when the truck needs one. For the wider picture, read how lenders review a business with no track record on our startup equipment financing page.
Is it better to lease or finance a commercial truck?
The better question is what you want to own when the term ends.
A lease leaves the truck with the lessor during the term, and the end-of-term options depend on the lease type. A fair market value lease prices the buyout at what the truck is worth then, while a $1 buyout lease is built for keeping it.
A loan or equipment finance agreement makes the business the owner from day one. Neither wins every time. Ask a specialist to compare both for your truck, and consult your tax advisor about the tax side.
What does it mean to refinance a truck loan?
Refinancing replaces an existing truck loan with a new one, usually to change the payment, the term or the lender.
A new lender needs the payoff amount, the current title details and the truck’s condition and mileage. Payoff comes first. The old lien comes off the title once it’s paid. Whether a swap makes sense depends on what the new terms cost over the whole loan, not just the monthly figure, and a longer term can lower the payment while raising what you pay overall, so compare the two loans side by side before you decide.
Do I need a CDL to own a commercial truck?
Not to own one, though driving certain trucks does take a commercial driver’s license.
Under 49 CFR 383.5, the CDL groups start at 26,001 pounds of GVWR or GCWR, and smaller trucks fall under ordinary licensing. Federal safety rules for interstate carriers start lower, at 10,001 pounds. A lender may ask who will drive the truck. Have that answer ready.
What slows a truck financing request down?
Paperwork that doesn’t agree with itself is the usual culprit, such as a VIN on the quote that differs from the title or an old lien nobody has paid off.
Small mismatches count. Missing proof of insurance and a vague equipment description come next.
Fix those before you apply. The review then has less to stall on. How long any step takes is up to the lender and the title office.
Ready to talk through your next truck?
Tell us what you’re buying, who’s selling it and where the business stands, and a Paramount Financial specialist will take it from there. Or start the credit application.