
Last updated: November 1, 2026
Restaurant Equipment Financing and Leasing
Compare true leases and loans for kitchen lines, refrigeration and dining rooms, new or used.
Restaurant equipment financing spreads the cost of a kitchen over time through a loan or a lease. With a true lease, the lessor owns the equipment, and you return, renew or buy it when the term ends.
A kitchen isn’t one purchase. It’s a hot line, a walk-in, a dish machine and a hood, and some of that can never leave the building. This page sits under our guide to equipment financing by industry and goes deeper on food service, from the owner signing for a first location to the group adding a tenth.
Paramount Financial offers true equipment leases, including operating leases, not only loans. So that’s where we’ll spend some time. Rather have a conversation? Talk to Paramount Financial’s team.
Restaurant equipment financing starts with what can leave the building
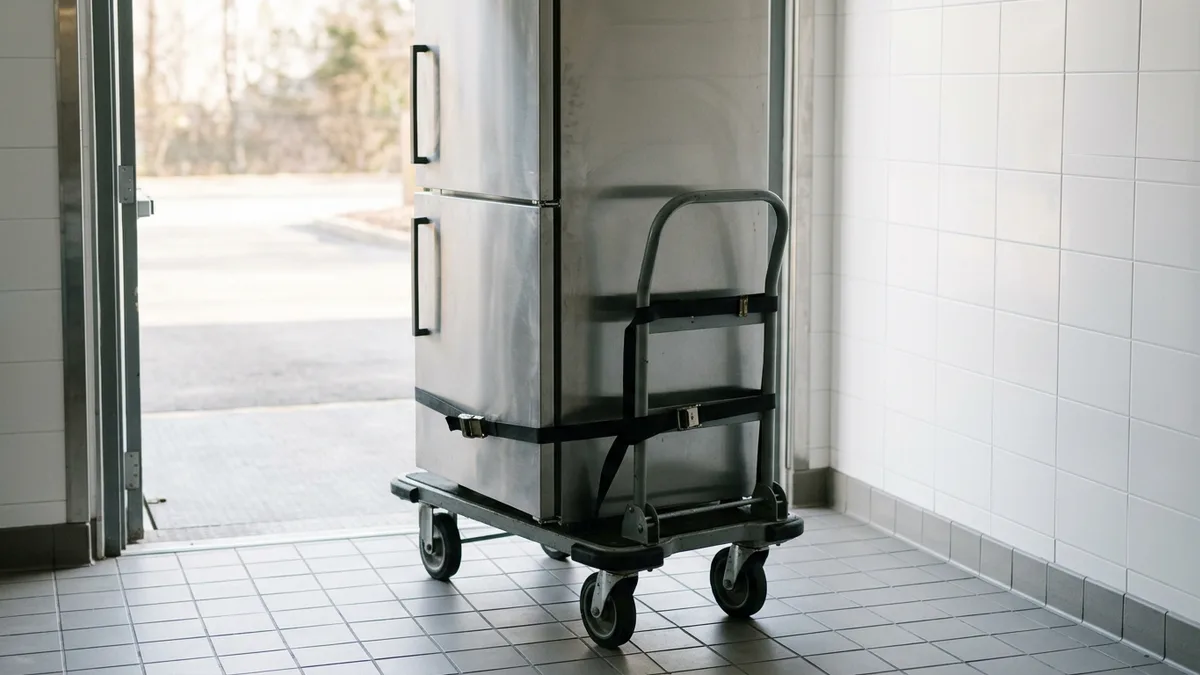
Most guides sort a kitchen by station. Try a plainer question: if this deal ended tomorrow, could someone wheel that unit out the back door? Lenders and lessors think about exactly that, because the equipment is their security, and a machine nobody can remove isn’t worth much to them.
Your landlord matters here. Most owners don’t see that coming. The bars below show how easily each group leaves.
It rolls out
Vulcan ranges, True reach-ins, Hobart mixers, fryers, slicers, the point-of-sale terminal at the host stand. They unplug. They sell again. Standard units like these are the simplest kitchen equipment to lease or to pledge.
It’s hooked up
Dish machines, combi ovens, ice makers, anything on a gas or water line. Getting one out takes a plumber or a gas fitter. So does getting one in. Ask whether that installation can sit inside the financing request.
It’s built in
Type I exhaust hoods, ductwork, fire suppression, grease interceptors, a walk-in assembled on site. Attached to a rented building, these can count as fixtures. Under UCC Section 9-334, a lender’s claim on fixtures generally ranks behind the owner’s unless the owner consents or another exception applies. That’s why you may be asked for a landlord waiver.
Restaurant equipment leasing: true lease or lease to own?
A true lease lets a restaurant use equipment for a set term while the lessor stays the owner, and the business returns it, renews or buys it at fair market value when the term ends. A lease to own ends with the business keeping the equipment for little or nothing extra.
Under UCC Section 1-203, a lease you can’t cancel, with an option to buy for a nominal amount, generally counts as a security interest, which means the paper says lease while the law sees something closer to a loan. A $1 buyout is the classic case. Same machine. Different deal.
Ask before you sign any lease
Want the detail? Start with the fair market value lease, then read operating lease versus finance lease.
Kitchen equipment, unit by unit
| Equipment | What ages it | Structure worth pricing first |
|---|---|---|
| Ranges, fryers, charbroilers | Heat and hard use, mostly repairable | A loan, an equipment finance agreement or a $1 buyout |
| Reach-ins and walk-in coolers | Compressors, gaskets, refrigerant rules | Own it if it’s staying; a lease if the space may change |
| Dish machines | Hard water and constant cycles | A lease or a loan, compared with the service contract |
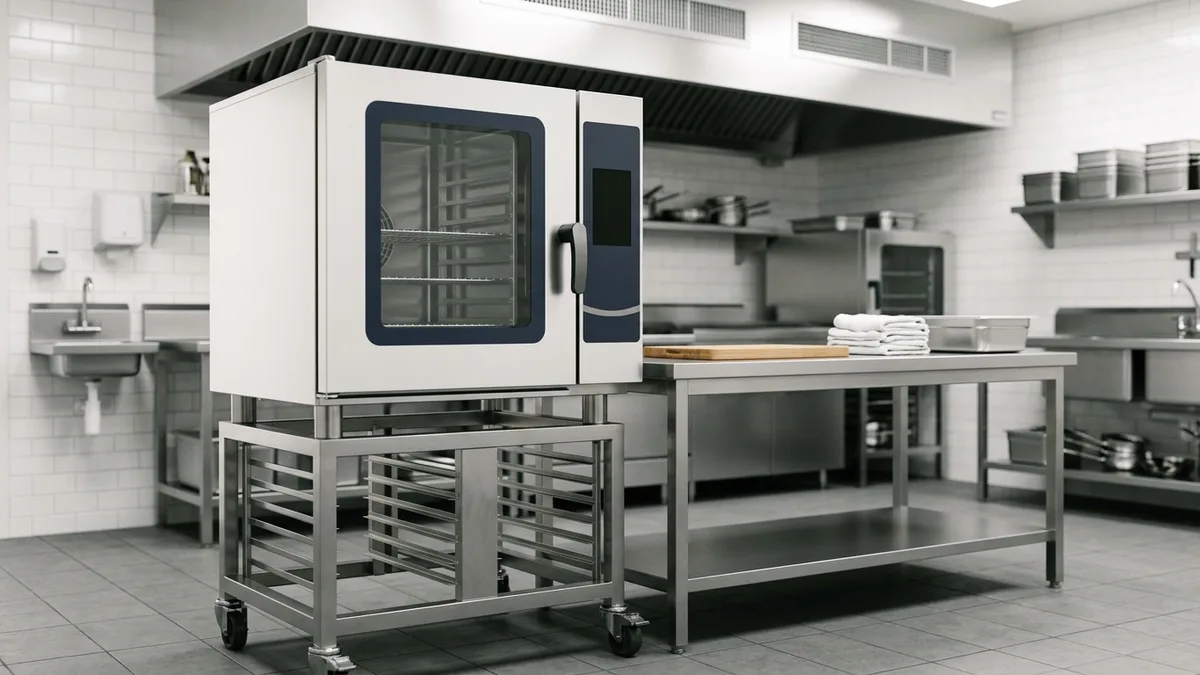
| Combi ovens | Controls and software | A fair market value lease, if you’d trade up |
| Point-of-sale hardware | Software and payment changes | A true lease with a short term |
| Hoods and fire suppression | Code changes more than wear | A loan, with the landlord’s written consent |
Treat that last column as a place to begin. It isn’t a rule. Get both prices, because a concept that changes its menu every two years and one that’s fried the same chicken since opening day shouldn’t sign the same paper, even for the same fryer. Our guide to leasing versus buying equipment walks through the decision.
Used restaurant equipment financing: what to check first
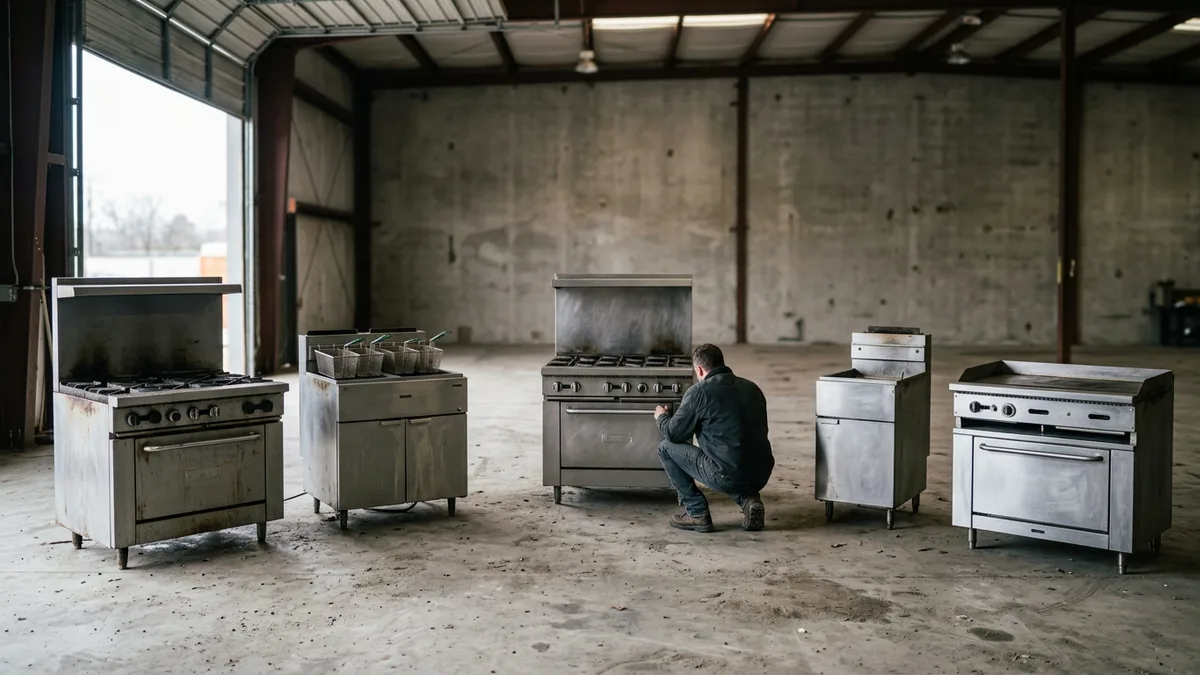
Restaurants close. Their kitchens end up with dealers and at auctions, and a used range can be a real bargain. It can also be somebody else’s problem. With no current price list to measure against, a lender leans harder on age, condition and what the unit would bring on resale, which is why the checklist below matters more than the asking price.
Your health department enforces its own version of the FDA Food Code, and the edition it follows may not be the latest, so a unit that passed in one county isn’t automatically fine in yours. Call before it ships. Our guide to used equipment financing goes further on older units.
Opening, expanding or replacing a unit
The same oven is a different purchase depending on why you’re buying it.
Be fair to the alternatives. An SBA 7(a) loan can pay for machinery and equipment, up to the program’s $5 million maximum, and because the government backs it, it can be among the most competitive ways to borrow. It also takes good credit, a solid plan and time, with no guarantee. Weigh that against the date your kitchen has to open.
Why every kitchen dollar gets a hard look
$1.55 trillion
in U.S. restaurant and foodservice sales, the 2026 projection published in February
Source: National Restaurant Association, 2026 State of the Restaurant Industry release
42%
of operators reported their restaurant wasn’t profitable in 2025
About $4,000
a year in energy costs a full suite of ENERGY STAR certified kitchen equipment could save, by the program’s estimate
Get these straight before you sign
Keep reading
What restaurant owners ask before they sign
Is it better to lease or buy restaurant equipment?
Short answer: own what you’d keep for a decade and lease what you’d swap out in a few years. A range or a worktable sits in the first group, while a connected combi oven or a point-of-sale terminal often fits the second. Plenty of kitchens do both. Price both.
Is lease to own the same thing as a lease?
Usually not, at least legally. If you can’t cancel and you can buy the equipment for a nominal amount at the end, UCC Section 1-203 generally treats the deal as a security interest, so it works like a loan. Ask how the contract is structured before you compare it with a true lease.
Can you finance used restaurant equipment?
Lenders and lessors do finance used kitchen equipment, though they look harder at age, condition, the seller and resale value. Auction and private sales usually bring more paperwork. Serial numbers help. So does a seller who can show the unit is free of liens.
What credit score do you need for restaurant equipment financing?
No single score decides it, because each lender sets its own standards and weighs them against the rest of the business. Time operating, cash flow, the property lease, the equipment and the owner’s experience can all count, and a lender that can resell the equipment may read those differently than one that can’t. Ask any lender what it looks at. Then compare the answers.
What do you need to apply for restaurant equipment financing?
Three things do most of the work: an itemized quote, basic details on the business and its owners, and a clear picture of the space. Many lenders also ask for bank or financial statements on a larger request. Keep the property lease handy. It comes up more than people expect.
Why would a lender care about my landlord?
Your landlord may have a claim on anything attached to the building, and that claim can outrank the lender’s. A signed landlord waiver settles who may remove the equipment if the deal ends. Get it early. Hoods and walk-ins raise the question most often.
Does Section 179 apply to restaurant equipment?
It can, and the limits depend on the tax year. For tax years beginning in 2026, IRS Publication 946 (2025 edition) puts the maximum Section 179 deduction at $2,560,000, reduced once qualifying property placed in service tops $4,090,000. Structure matters too, since you can generally depreciate leased property only if you keep the incidents of ownership. Consult your tax advisor before you pick a structure for tax reasons.
Have a quote for your kitchen? Start there.
Leave your details and we’ll talk through the quote and your target opening or install date, or start your application online instead.