
Last updated: November 2, 2026
Forestry Equipment Financing for New and Used Logging Machines
Compare loans and true leases for skidders, feller bunchers, loaders and log trucks, side by side.
Forestry equipment financing spreads the cost of a skidder, feller buncher or log loader over time through a loan or a lease. A loan makes you the owner from day one; in a true lease, the lessor owns the machine.
Nobody in the woods buys a machine on its own. A skidder has to keep up with the buncher ahead of it and the loader behind it, so any purchase changes the whole crew’s day, from the first stem cut at daylight to the last truck scaled at the mill. This page sits under our guide to equipment financing by industry and goes deeper on logging, from a two-machine thinning crew to a full side.
Paramount Financial offers true equipment leases, including operating leases, not only loans. We’ll cover both. Rather talk it through? Talk to Paramount Financial’s team.
Forestry equipment financing starts with the whole side
Loggers call a crew and its machines a side. It runs like a chain. Every stem passes from one machine to the next, and the slowest link sets the day’s loads, no matter what the others could do alone on a dry morning with good ground under them.
So a new machine in the wrong spot buys you very little. A faster buncher ahead of a tired skidder just piles wood in the woods. Find the link holding up the trucks. Finance that one first.
A whole-tree side: four stops, stump to truck
1
Feller buncher
Cuts the stems and lays them in bunches. Saw teeth, the head and the undercarriage eat the repair budget.
2
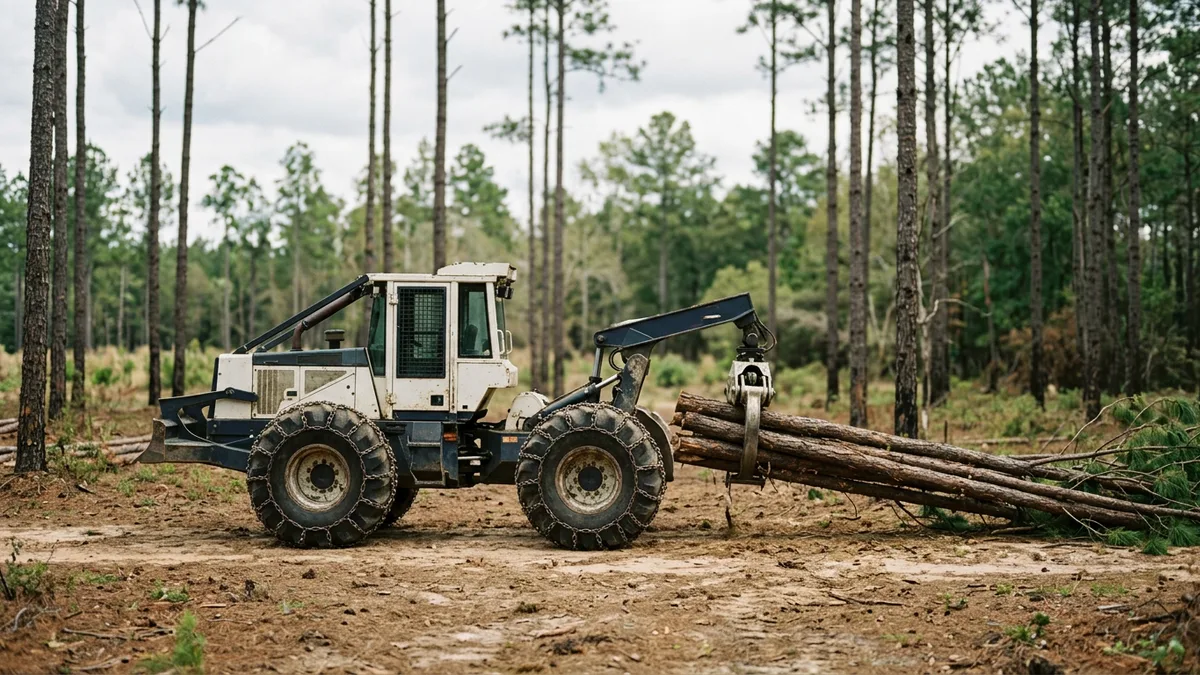
Grapple skidder
Drags those bunches to the landing, turn after turn. Tires, chains and the center joint take the beating.
3
Delimber and slasher
Strip the limbs and cut stems to length at the landing. Often mounted on a carrier or a trailer, so ask what’s included.
4
Knuckleboom loader
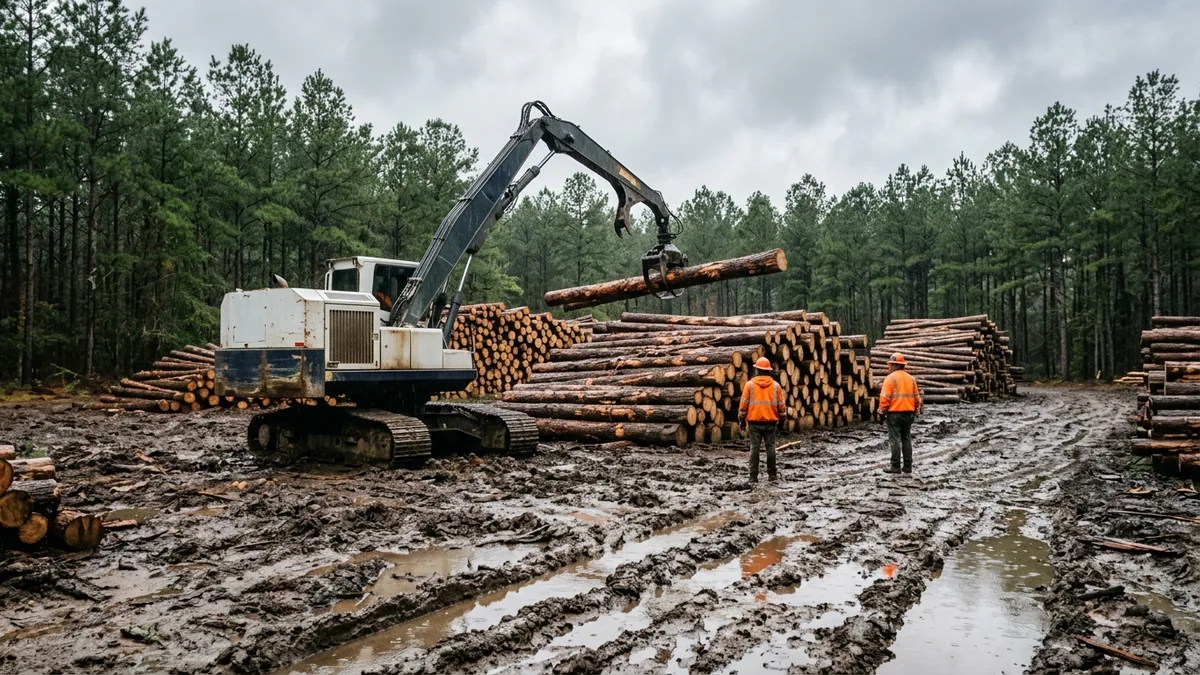
Sorts the wood and builds the load. Nothing leaves until it’s done, so a down loader stops the trucks cold.
A cut-to-length side: three stops
1
Single-grip harvester
Fells, limbs and bucks right in the stand. Its head and measuring electronics do the work of a landing crew.
2
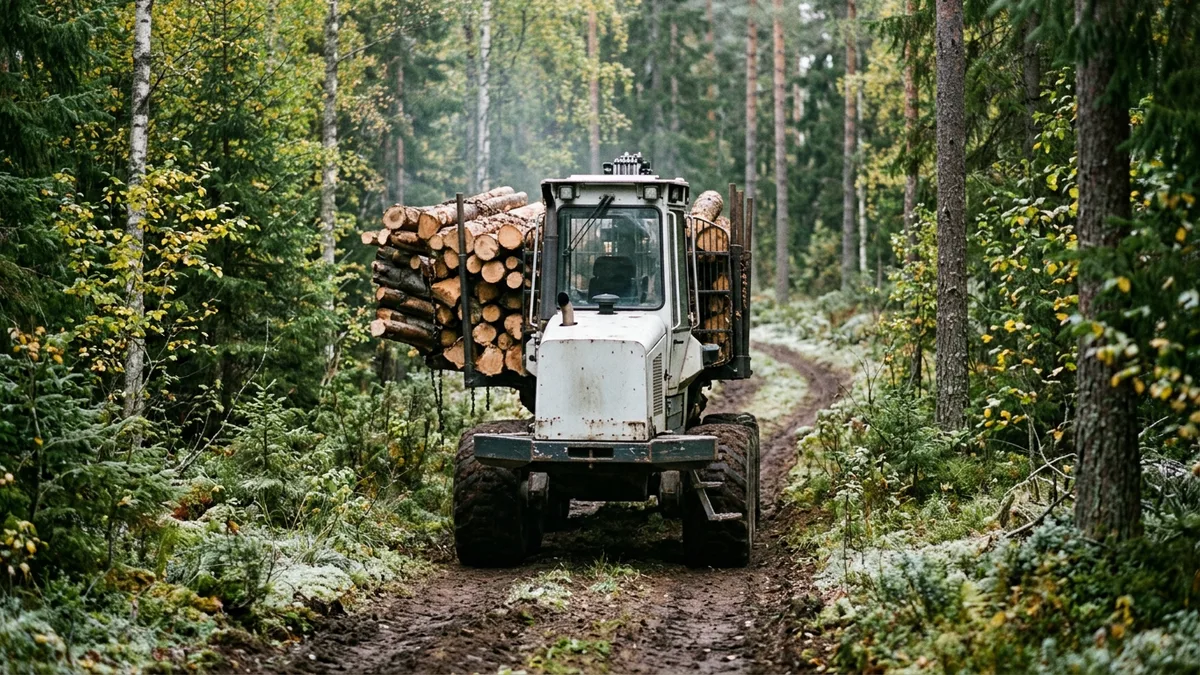
Forwarder
A forwarder picks up the cut logs, carries them out in its bunk and piles them at the landing.
3
Log truck
On a smaller job the forwarder may load the truck itself, which can leave no separate loader to pay for.
Fewer machines. Dearer ones, usually. Walk a southern pine job and you’ll likely see a whole-tree side, while cut-to-length turns up more around the Lake States and the Northeast, and plenty of crews mix the two anyway.
Forestry equipment financing: loan, lease or in between
Sign a loan or an equipment finance agreement and the logging business owns the machine from day one, while the lender keeps a security interest until the last payment clears. With a true lease, the lessor stays the owner, and at the end of the term you hand it back, renew it or buy it at fair market value.
And the $1 buyout? That’s the odd one. The paper says lease, you’re headed for ownership, and the law often calls it a loan.
A rule of thumb for the woods
Still torn? Read leasing versus buying equipment next.
Logging machines, one by one
| Machine | What wears first | Structure worth pricing first |
|---|---|---|
| Feller buncher | Undercarriage, saw head, swing bearing | A loan or an equipment finance agreement, if it stays for years |
| Grapple skidder | Tires and chains, center joint pins, the grapple | A loan, an equipment finance agreement or a $1 buyout |
| Knuckleboom loader | Boom pins, hydraulics, the carrier or trailer | A loan, quoted together with whatever it’s mounted on |
| Delimber and slasher | Knives, saw bar, feed rollers | On the same request as the loader, if they travel together |
| Single-grip harvester | The head, its sensors and electronics | A fair market value lease, if you’d trade up |
| Forwarder | Bogies, tires or tracks, the crane | Either one, set against how long the work lasts |
| Log truck and trailer | Frame, bunks, miles more than hours | A loan or a TRAC lease |
Read that last column as a first guess. Say you’ve had ten years of steady mill work and your neighbor just landed a two-year thinning job: you two shouldn’t sign the same paper, even on the same skidder from the same dealer. Get both prices.
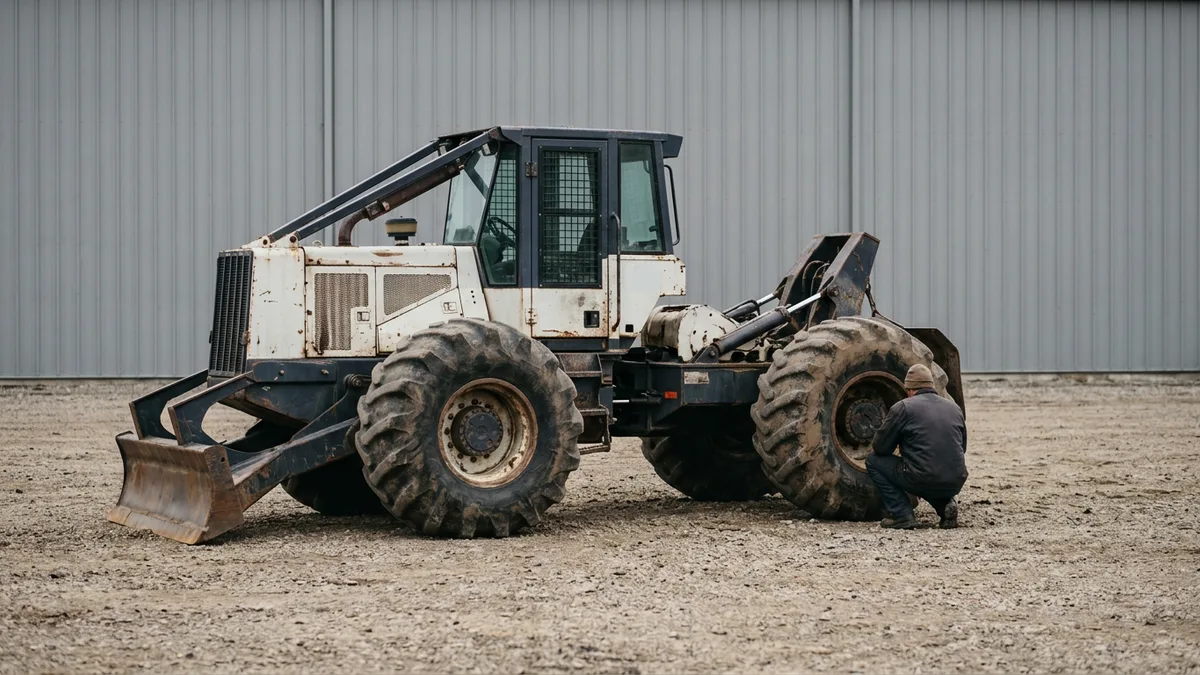
Used logging equipment financing: hours, rebuilds and the cab
Hours come up first. Fair enough. Say two skidders sit on one lot, one with high hours and a rebuilt engine, the other with fewer hours and nothing ever opened up: the first can be the better buy, so expect a lender to ask for the story behind that meter.
Now climb up and check the cab. Under OSHA’s logging standard, 29 CFR 1910.266, a machine built after August 1, 1996 needs rollover protection plus a cab fully enclosed with mesh, while older ones fall under a separate rule. Some states enforce their own version, so it’s worth a call. Dealers and private sellers get more room in our guide to used equipment financing.
Mud, mill quotas and the payment calendar
Logging money doesn’t come in even months. A wet spring shuts a tract, a mill with a full yard cuts quotas, and the payment’s still due on the first. Before you sign anything, ask any lender whether the schedule can follow your season, what that does to the total cost over the full term, and what happens if a tract stays shut.
What helps a lender read a logging business
An SBA 7(a) loan deserves a fair look as well. It can pay for machinery, and the government backing can make it one of the most competitive ways to borrow, but it also takes strong credit, a solid plan and months of patience, with no guarantee at the end. Tracts don’t always wait.
The logging trade, from the public record
16,680
logging equipment operators employed in U.S. forestry and logging in 2025
Source: U.S. Bureau of Labor Statistics, Forestry and Logging: NAICS 113
August 1, 1996
the build date that decides which federal cab rule a used logging machine falls under
Source: OSHA, 29 CFR 1910.266(f)(3)
$2,560,000
maximum Section 179 deduction for tax years beginning in 2026, before the phase-out
Source: IRS Revenue Procedure 2025-32. Consult your tax advisor.
Four things to line up before you apply
More for logging and land-clearing crews
What loggers ask before they finance a machine
Should a logging company lease or buy its machines?
Short answer: own what you’ll run until it’s worn out and lease what you’d trade in a few years. Skidders and loaders usually land in the first group. A harvester full of electronics can land in the second. Price both.
Can you finance a used skidder or feller buncher?
Lenders and lessors do finance used forestry machines, though hours, condition, the seller and resale value all get a harder look. An auction or a private sale usually adds paperwork. Plate photos help. So do rebuild receipts.
What credit score do you need for logging equipment financing?
No single score decides it, because each lender sets its own standards. Time in the woods, cash flow, mill relationships and the machine itself can all count, and a lender that knows how to resell a skidder may read them differently than one that doesn’t. Ask what it looks at. Compare the answers.
What do you need to apply for forestry equipment financing?
Start with a seller’s quote naming the serial number, then add basic details on the business and its owners. Bank statements or financials may come up on a larger request. Scale tickets can fill in what statements don’t show.
Can a new logging business get equipment financing?
It happens, but expect more questions than an established crew gets. Lenders reviewing a newer logging business tend to look harder at the owner’s years in the woods, any signed mill or tract work and the machine itself. Startup equipment financing covers what to line up.
How is a log truck different from the machines in the woods?
A log truck is a titled highway vehicle, so a lien usually shows on the title instead of resting on a UCC filing alone. It also falls under the federal heavy vehicle use tax. The Form 2290 instructions for July 1, 2026 through June 30, 2027 tax qualifying logging vehicles at reduced rates, so consult your tax advisor on whether yours qualifies.
Does Section 179 apply to logging equipment?
It can, and the limits change by tax year. For tax years beginning in 2026, IRS Revenue Procedure 2025-32 sets the maximum Section 179 deduction at $2,560,000, reduced once qualifying property placed in service tops $4,090,000. Structure matters too, because a true lease and a purchase are treated differently. Consult your tax advisor before you pick one for tax reasons, and see our Section 179 deduction guide.
Got a quote on a machine? Start there.
Leave your details and we’ll talk through the machine, the seller and your next tract, or start your application online instead.