
Last updated: November 12, 2026
POS System Financing for Restaurants and Retailers
Spread the cost of terminals, handhelds, printers and card readers, and see which POS costs count as equipment.
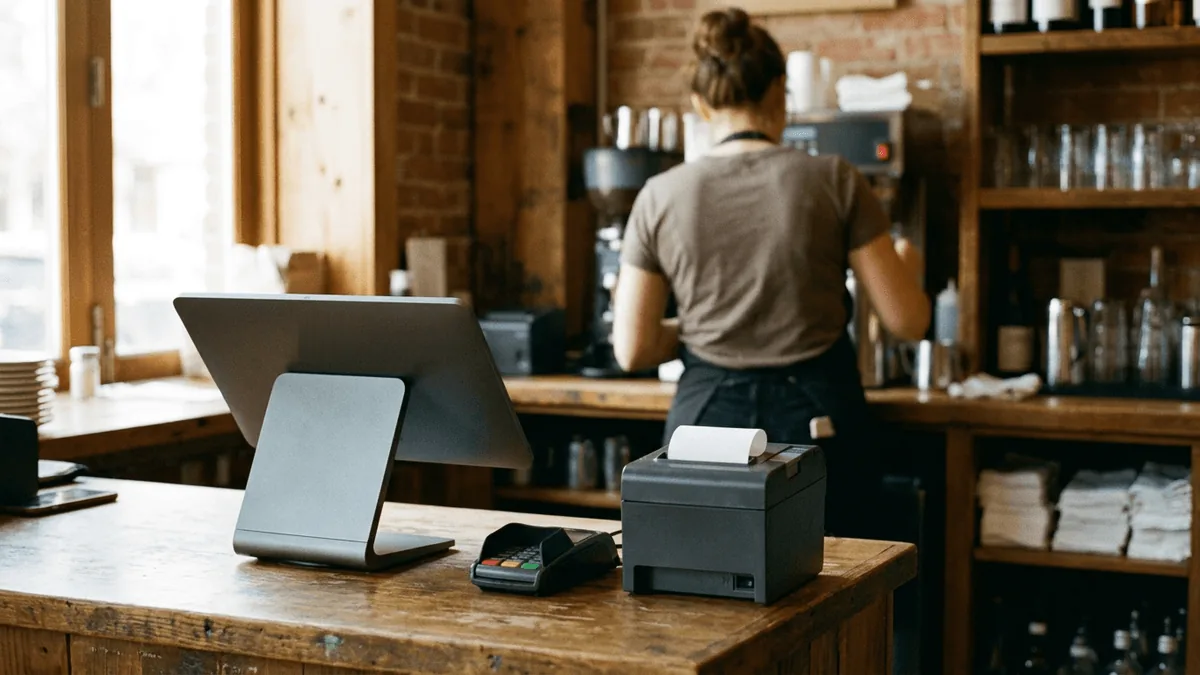
POS system financing pays for the hardware at the register, such as terminals, tablets, printers and card readers, over a set term, so a restaurant or shop can open or upgrade without paying for everything up front.
Restaurants are the first audience here, followed by shops with a counter. A point-of-sale system bundles three separate purchases: hardware, a software plan and card processing. Only the hardware is equipment.
The wider picture is in Paramount Financial’s commercial equipment financing overview. Kitchen-side gear has its own page on restaurant equipment financing, and the subscription side sits under software financing.
What POS system financing covers
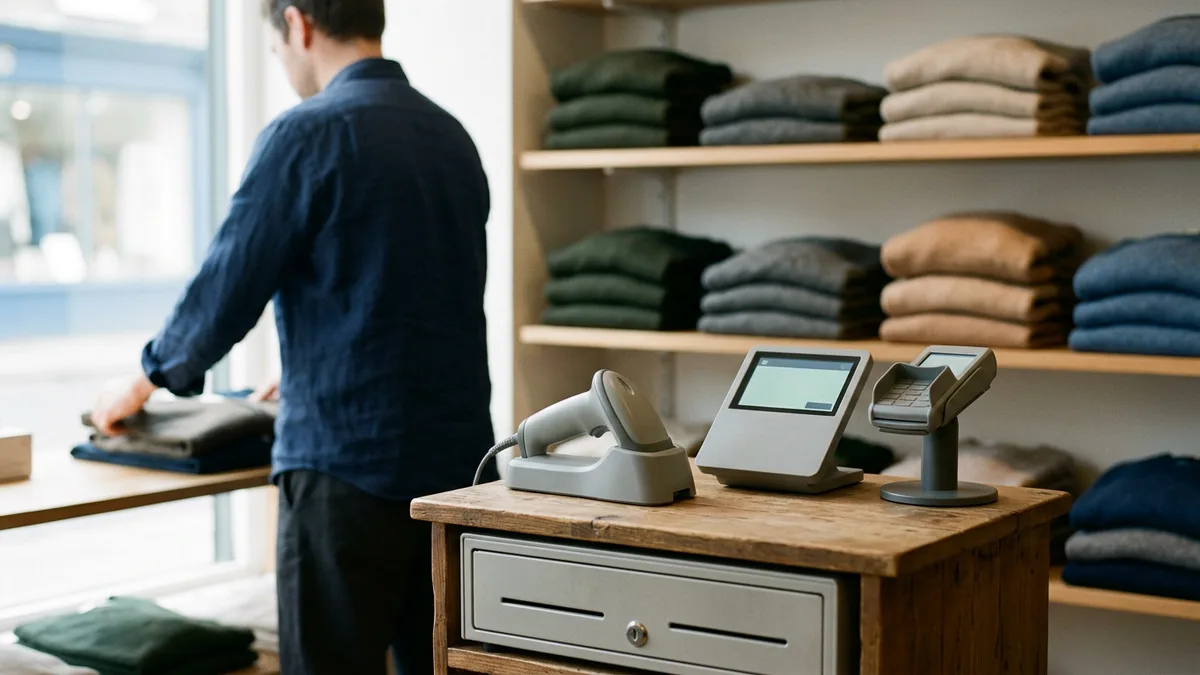
POS system financing is an arrangement where a lender pays the seller for point-of-sale hardware, such as terminals, tablets, kitchen display screens, receipt printers and card readers, and the business repays over a set term with the hardware as collateral. UCC Section 2A-103 defines a lease as a transfer of the right to possession and use of goods for a term in return for consideration, so the lessor keeps title and the business pays to use the hardware.
UCC Section 9-102(a)(33) defines equipment as goods other than inventory, farm products or consumer goods, which is why terminals, printers and card readers fit and a subscription doesn’t. A software plan and card processing aren’t goods.
A restaurant adding a bar and a patio needs handhelds for the floor, a printer at each station and a kitchen screen. Count every piece before asking for a quote.
What counts as equipment in a POS system
Forget the total for a minute. Read the quote line by line and mark which items are hardware, because that sort decides what an equipment lender can look at and what it can’t. Here’s how the pieces usually fall.
| Piece | Examples | What to ask the seller |
|---|---|---|
| Terminals and registers | Countertop terminals, all-in-one stations, tablet stands | Make, model and serial number for each unit |
| Handhelds | Tableside tablets and phone-sized order devices | Whether cases and charging docks sit on the same invoice |
| Kitchen and bar gear | Kitchen display screens, bump bars, ticket printers | Whether mounts, cabling and installation are separate lines |
| Counter extras | Card readers, PIN pads, scanners, cash drawers, receipt printers | Whether each is its own line or bundled with a terminal |
| Network | Routers, switches, a backup connection | Who supplies it and who installs it |
| Software | Ordering, inventory, loyalty and reporting plans | Whether it’s a subscription, and what happens to the hardware if you cancel |
| Card processing | Fees charged on each sale | It’s a fee, not equipment, so it stays out of an equipment quote |
Finance, lease or use the vendor’s plan
Whether a deal written as a lease is a true lease or a financing in disguise depends on its facts, according to UCC Section 1-203, so ask who owns the hardware at the end. With a loan or an equipment finance agreement, the business owns the terminals from day one and the lender holds a security interest. With an equipment lease, the lessor owns them during the term. A fair market value lease usually ends with a choice to return, renew or buy, while a $1 buyout lease is built so the business keeps the hardware.
Terminals get swapped when the software outgrows them, so a shop that runs its hardware until it quits and a shop that wants newer units on a schedule don’t need the same structure. Ask one more thing. Does the hardware work with any software provider, or only one?
When the POS company offers the money
Some POS providers offer funding inside the platform. Nation’s Restaurant News described one version in October 2026: a cash advance repaid through split funding, which takes a share of each card sale instead of a fixed payment. Different product. Ask whether the offer is a loan, a lease or an advance, and add up everything repaid, not only the first number.
Food trucks, counters and unattended machines
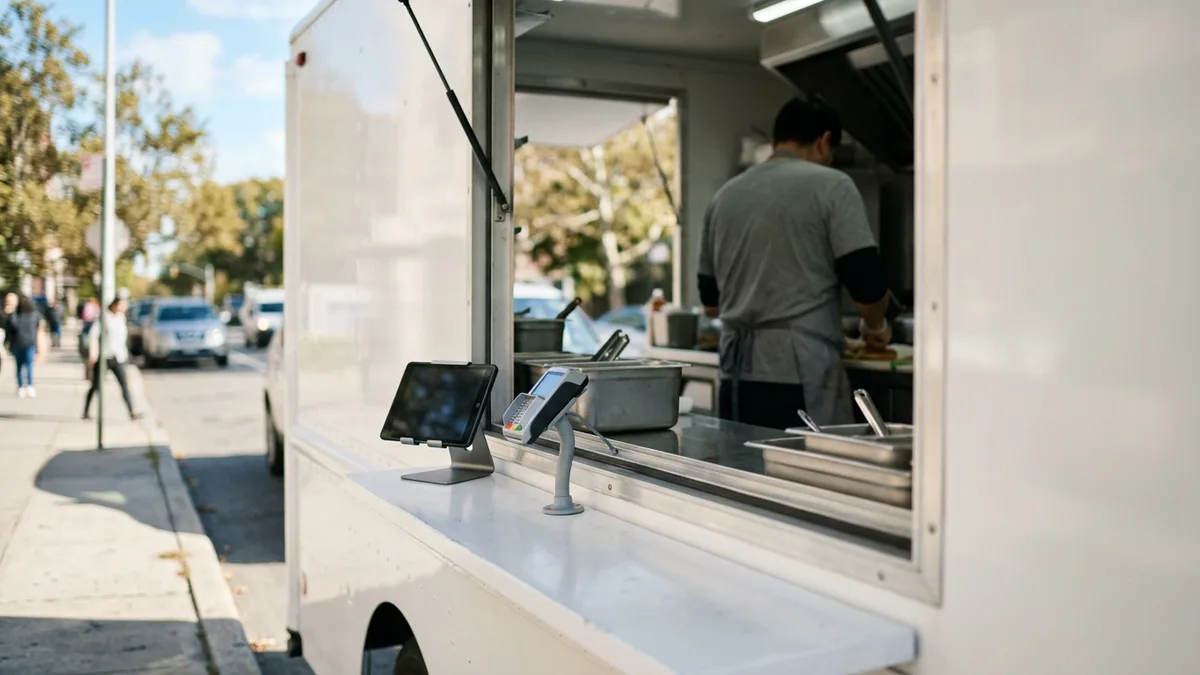
Not every POS hangs on a restaurant wall. A food truck runs a tablet and a reader at the serving window, a boutique runs a scanner and a register drawer, and a route operator needs a reader inside every machine. Food truck financing and vending machine financing cover those businesses in more detail.
Card data adds rules. The PCI Security Standards Council describes PCI DSS as a baseline of technical and operational requirements to protect payment account data, aimed at entities that store, process or transmit cardholder data. Ask how the hardware handles it before it’s installed. Ask early.
Lining up the paperwork before the order
Hardware often has to be installed and tested before the doors open, so the opening schedule sets the order date, not the other way around. The restaurant equipment financing for startups guide covers that side. Paper first. Have these ready before anything is ordered:
Routers, switches and back-office computers sit under IT equipment financing.
Two more guides help before an order goes in: equipment financing requirements and leasing vs buying equipment. Starting from scratch? The how to start a restaurant and how to start a coffee shop guides list the equipment in the order a place opens.
Three numbers behind the register
$1.55T
Projected 2026 sales across the US restaurant industry
17.1%
Share of US retail sales made online in the second quarter of 2026, seasonally adjusted
Source: U.S. Census Bureau, Q2 2026
$2,560,000
Maximum Section 179 deduction for tax years beginning in 2026
Source: IRS, Publication 946
Ways to pay for POS hardware
Questions about financing a POS system
Can you finance a POS system?
Short answer: the hardware can be financed as equipment, while the software plan and card processing are billed as services. UCC Section 9-102(a)(33) defines equipment as goods other than inventory, farm products or consumer goods, which is why terminals, printers and card readers fit and a subscription doesn’t. Ask the seller to price each on its own line.
Is it better to lease or buy POS hardware?
The better question is how long you plan to keep it. Under UCC Section 2A-103, a lease is a transfer of the right to possession and use of goods for a term, so a business leasing terminals doesn’t own them unless the lease gives it a buyout. Read the end-of-term options and the buyout line before signing, because a fair market value lease and a $1 buyout lease end very differently.
Does POS financing cover software and installation?
That depends on the lender and on the invoice. Installation sometimes rides along. Software is the open question, because a plan billed as a subscription is a service and a lender decides case by case whether to include it, so ask before the order goes in. The software financing page covers that side.
Can a new restaurant finance a POS system before it opens?
Lenders reviewing a newer business tend to look harder at the equipment and the owner’s experience, so the quote and the opening schedule matter. Bring serial numbers. Bring a delivery date. The startup equipment financing guide shows how a first application gets read.
How is POS financing different from a merchant cash advance?
An equipment loan or lease is tied to specific hardware, while a cash advance is repaid through a share of card sales and isn’t tied to the equipment at all. Compare the total repaid, how repayment behaves in a slow month, and what happens to the balance if you switch card processors before it’s paid off. Read every line.
Can an SBA loan pay for a POS system?
Possibly. The SBA lender decides. SBA’s 7(a) page lists purchasing and installation of machinery and equipment, and short- and long-term working capital, among the allowed uses, though what a given lender accepts for a small hardware purchase varies. The equipment financing with an SBA loan guide walks through the options.
Does Section 179 apply to POS hardware?
It can for qualifying equipment placed in service during the 2026 tax year, though whether a given terminal setup qualifies is a question for a tax advisor. IRS Publication 946 explains the property rules, the Form 4562 instructions cover claiming the election, and the Section 179 deduction guide has the current-year figures. Consult your tax advisor.
Ready to finance your POS system?
Tell us what’s going in, new or refurbished, and who’s supplying it, and a member of our team will follow up.